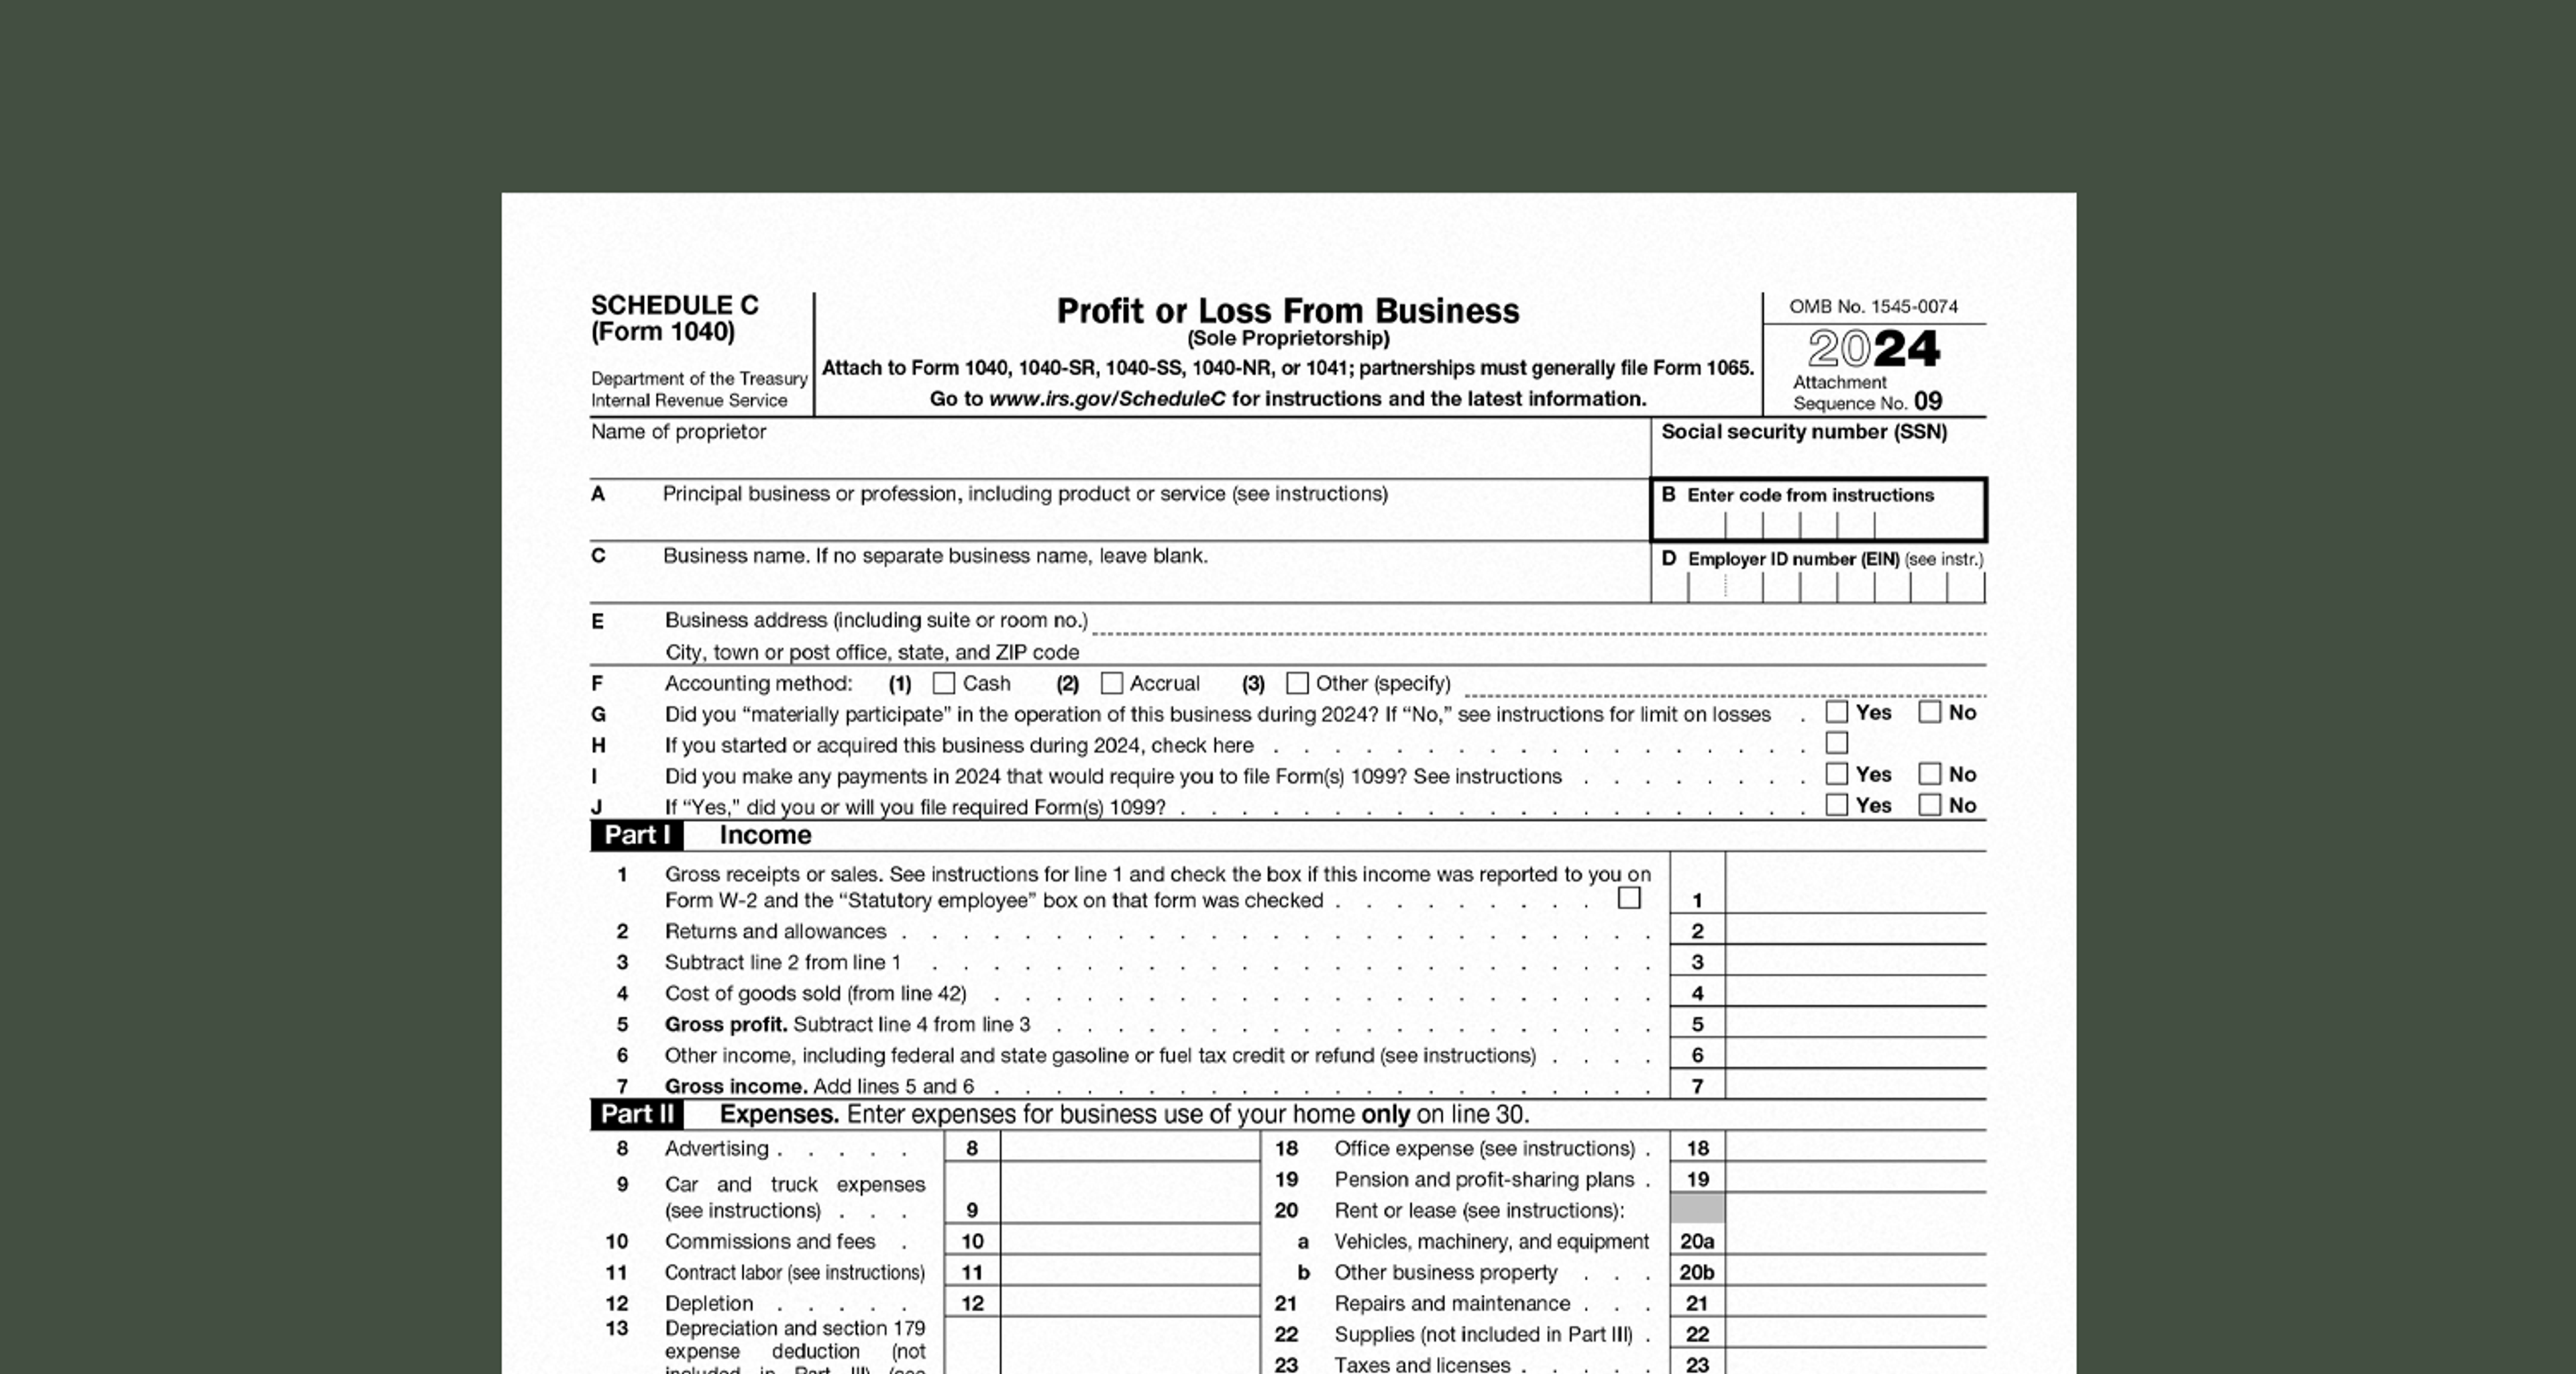
If you file taxes as a sole proprietor, Schedule C is the IRS form you’ll use to report business profit or loss. Here’s who needs to file it and how to fill out every line.
Schedule C (Form 1040) is the IRS form sole proprietors and single-member LLC owners use to report their business income and expenses. Your net profit from Schedule C carries over to your Form 1040 and to Schedule SE, where it’s used to calculate self-employment tax.
So, who exactly has to file Schedule C? If you freelanced, took on subcontract work, drove your own truck, ran a side business, or earned off-farm income as a producer this year, read on. In this guide, we’ll cover more detail on who needs to file the form, what to gather before you fill it out, and each line of Schedule C.
Key takeaways
Schedule C reports business profit or loss for sole proprietors and single-member LLCs that haven’t elected to be taxed as a corporation.
Your net profit numbers will then flow into Schedule 1 (Form 1040) and Schedule SE to figure self-employment tax. You’ll typically owe self-employment tax if your net earnings from the year are $400 or more.
File a separate Schedule C for each business you run.
For producers, farm income goes on Schedule F. Non-farm activities, like agritourism or selling processed products, go on Schedule C.
Schedule C is due with your Form 1040 on April 15.
What is Schedule C, Form 1040?
Schedule C is part of your U.S. Individual Tax Return (Form 1040). Taxpayers use it to calculate and report profits or losses from business they operate or professions they practice as a sole proprietor.
If you haven’t incorporated or filed paperwork to become an LLC or corporation, you’re probably a sole proprietor and have to file Schedule C with your tax return. You’ll also file Schedule C if you’re a single-member LLC, meaning you’re the sole member of the LLC.
Getting ready for tax season? Ambrook Tax helps you file straight from your books.
Who needs to file Schedule C?
If you are not incorporated, not a partnership or multi-member LLC, and you haven’t elected S Corporation status, you’re probably a sole proprietor. That means you’ll need to file Schedule C.
You don’t have to create a sole proprietorship: according to the IRS, you’re automatically considered a sole proprietor if you continuously and regularly engage in an activity for income or profit (i.e., to make money).
Single-member LLCs also have to file Schedule C unless they’ve elected to be taxed as a C corporation or S corporation.
Finally, if you’re a statutory employee (in which case, you’ll have Box 13 checked on your W-2), you’ll also report that income and any related expenses on Schedule C. Your employer already withholds Social Security and Medicare taxes from your pay, so you don’t owe self-employment tax on this income.
Schedule C by industry
Here are a few examples of income and expenses you’d report on Schedule C, depending on your industry.
| Industry | Examples of Schedule C income | Examples of Schedule C expenses |
|---|---|---|
| Construction | If you’re a sole proprietor, income from jobs you do as a general contractor or subcontractor. | Payments to subcontractors, materials, supplies, equipment, truck mileage, or liability insurance. |
| Trucking | As a business owner, revenue from freight and hauling. | Fuel and repairs, truck depreciation, or insurance. |
| Farming or ranching | Revenue from agritourism, event rentals, processed products like cheese or jam, or income from non-farm side work like construction or hauling jobs. (Custom hire work for other farms goes on Schedule F.) | Event supplies, advertising, contract labor, or insurance. |
| Food processing | Revenue from sales of processed or packaged products. | Ingredients, packaging, equipment, licenses, or utilities. |
When do farmers have to file a Schedule C?
The differences between Schedule F and Schedule C can be especially tricky to navigate if you run a farm or ranch, so let’s talk about when farmers need to file Schedule C.
You’re likely already familiar with Schedule F, which you’ll use to report any agricultural income. But if you get some of your income from non-farm sources, you’ll have to file Schedule C as well.
Here are more detailed examples of the income you’d have to report on Schedule C:
Working as a freelancer or contractor on the side in a non-farm trade. (Custom hire work, like planting, spraying, or harvesting for other farms, still goes on Schedule F, Line 7.)
Commodities you process in some way, like making and selling wine, cheese, jams or other processed products.
Educational, recreational, or tourism-related activities, like wedding venue rentals or corn mazes.
Agritourism, which for tax purposes is considered a “non-farm” business activity.
If you’re already reporting income or expenses on Schedule F, do not report them a second time on Schedule C.
What should you gather before filling out Schedule C?
Schedule C requires detailed information about your income and expenses to complete. Here are a few steps to help get everything ready before you start filling it out:
Grab your balance sheet and income statement if you have them, as well as your check register or any other record of your business’ transactions and documentation (receipts, invoices, etc.) to back those expenses up.
Make sure you’ve cleaned up the books for the year: categorize expenses, separate personal and business spending, reconcile accounts, and check if your accounting software has been keeping track of Schedule C income and expenses for you.
If you’re using Ambrook and do have your categories mapped to Schedule C boxes, export the Schedule C breakdown report from your settings.
If you’re reporting vehicle expenses, pull up your mileage log for each vehicle.
Locate basic information like your business name and contact information, your Social Security Number (SSN), Taxpayer Identification Number (TIN) and Employer Identification Number (EIN) if you have one.
Then, you’re ready to start on filling out Schedule C. Let’s walk through it line by line.
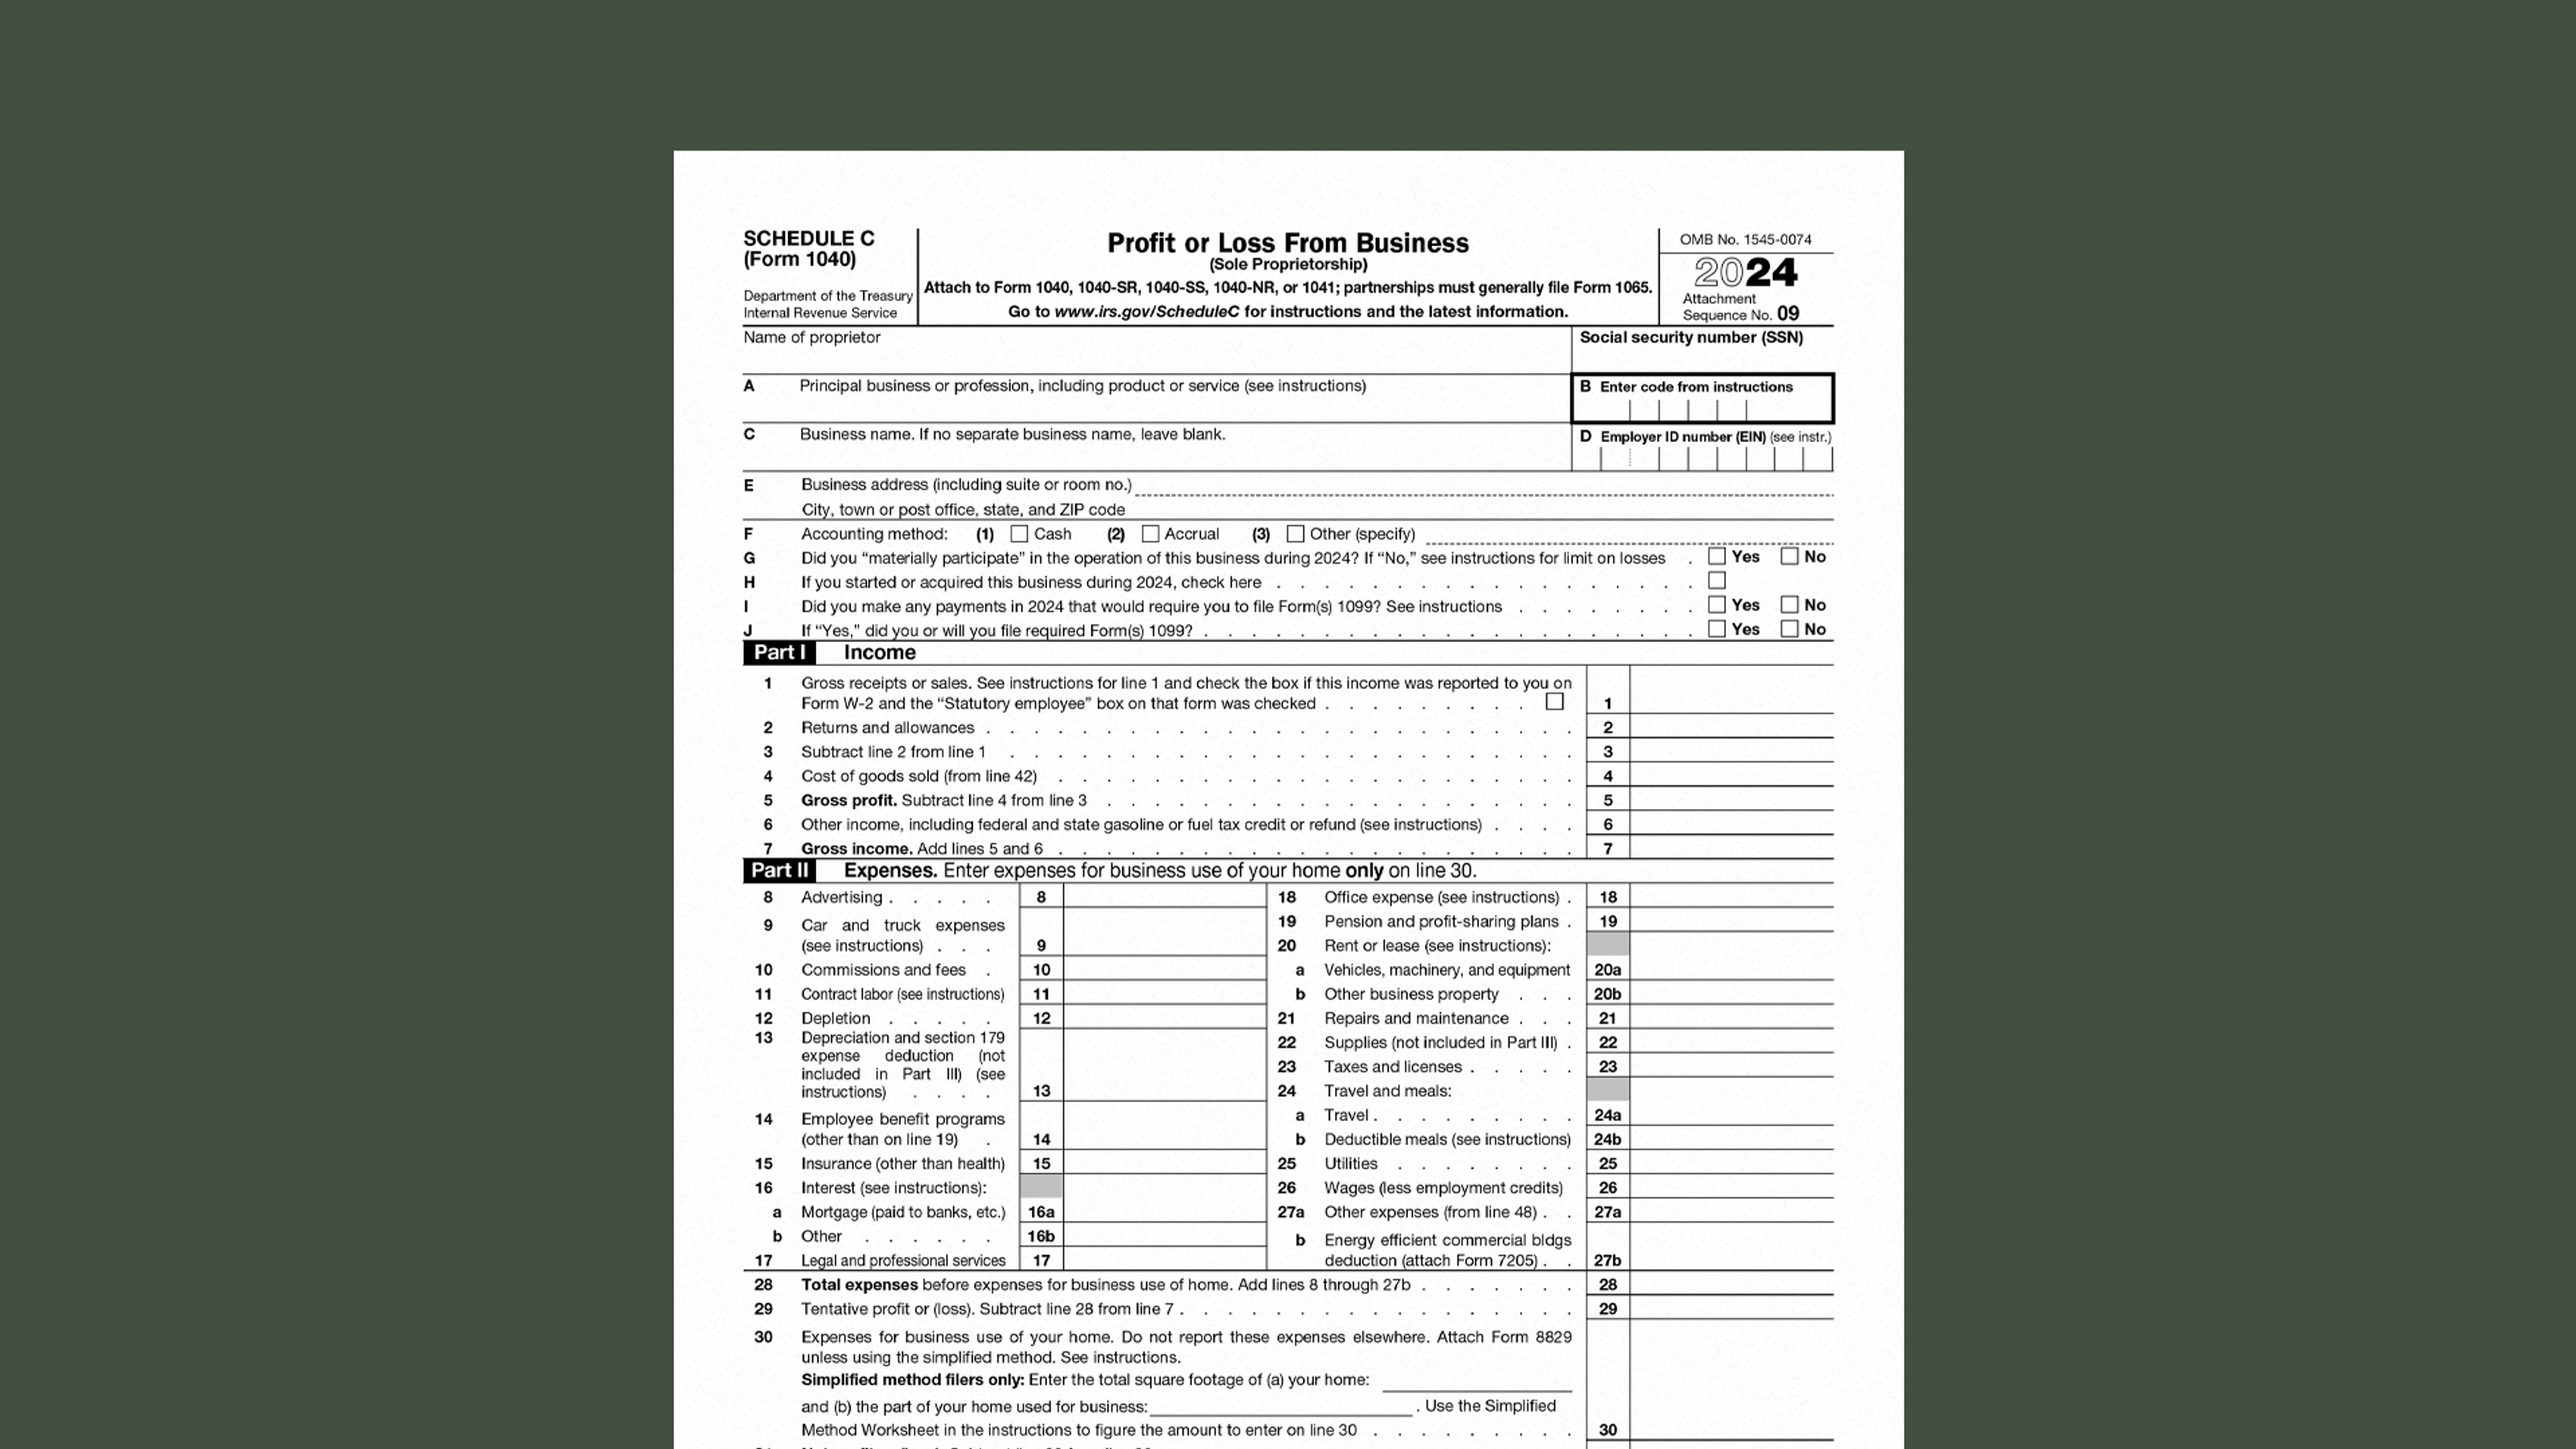
How to fill out Schedule C: A step-by-step guide
Basic Information Fields
Enter your name (if you’re the business proprietor) and your Social Security Number (SSN) at the top of the form.
Line A: Principal business or profession
Briefly describe the business you’re reporting income or losses for here, including your industry and the type of product or service you provide.
If you operate multiple businesses, complete a separate Schedule C for each one.
Line B
Enter the six-digit Principal Business or Professional Activity (PBA) Code that corresponds to your business. Select the code from the ‘Principal Business or Professional Activity Codes’ section at the bottom of the instructions to Schedule C on the IRS website, or on the last few pages of the PDF version.
Line C
Enter your business name here, if your sole proprietorship operates under a different name than your own.
Line D
Enter the employer identification number you applied for with Form SS-4 here, or leave it blank if you don’t have an EIN.
Line E
Enter your business address here.
Line F
Use these checkboxes to indicate whether you use the cash method, accrual method, or another method of accounting. If you check “Other,” you’ll need to specify which method you use. Remember that you have to file Form 3115 to change your method of accounting.
Line G
Use these boxes to indicate whether you materially (‘yes’) or passively (‘no’) participated in the business.
Generally speaking, you materially participate in the business if you participate in the activity on a “regular, continuous, and substantial basis” during the year. (However, rental activities are generally considered passive activities.)
The IRS has a series of tests for this: generally you materially participate if you spent more than 500 hours on the business, or spent more than 100 hours and at least as much as any other individual. You can find a full list of material participation tests in Publication 925 under ‘material participation tests.’
Line H
Check this box if you acquired the business during the tax year.
Line I and J
Check these boxes if you’re required to file a Form 1099 during the tax year, and whether you plan to file the required forms. If you paid someone who isn’t your employee $2,000 or more in the calendar year for their services, for rent, or for barter, you’ll probably have to file a Form 1099-NEC or 1099-MISC. Make sure to collect a Form W-9 so you have the payee’s taxpayer ID.
Part I: Income
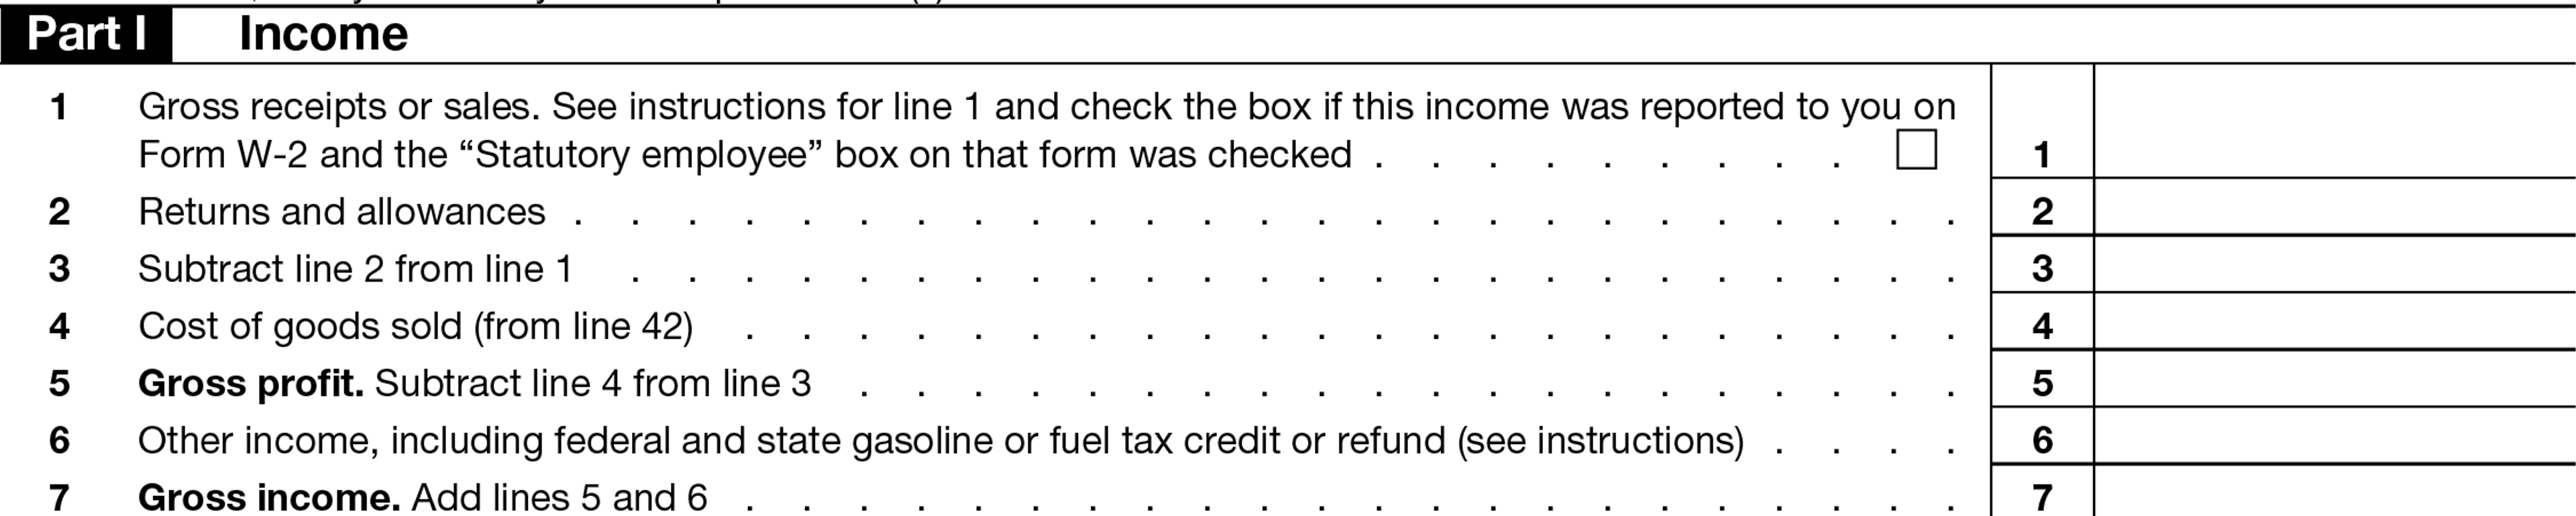
This part is about calculating the gross income and gross profit of the business.
Line 1: Gross Receipts or Sales
Enter your business’s gross receipts for the tax year: the total you took in from sales and services before subtracting costs, returns, or expenses. (Other types of business income, like interest on accounts receivable or scrap sales, go on Line 6.) Make sure to include business income reported to you on:
If you’re a farmer, don’t include farming-related income from Form 1099s. Report that on Schedule F instead.
If you receive a Form W-2 with Box 13 checked, enter your statutory employee income from Box 1 on that form on Line 1 of Schedule C and check the “statutory employee” box.
Line 2: Returns and allowances
If you issued refunds or credit to customers for returned goods or offered sales allowances (i.e., reduced the selling price of your products to certain customers) report those amounts here.
Line 3
Subtract Line 2 from Line 1.
Line 4: Cost of Goods Sold
If your business manufactures or purchases goods for resale, you can deduct the costs involved in manufacturing or acquiring them here. If you do, skip ahead and complete Part III first, then enter the resulting amount from Line 42 here.
For more information, check our guide to calculating cost of goods sold.
Line 5: Gross Profit
Subtract Line 4 from Line 3 to calculate your gross profit.
Line 6: Other Income
Use this section to report any other income your business earned that you didn’t enter on any of the other lines on Schedule C, including income from:
Recovered bad debts
Prizes and awards
Scrap sales
Federal and state gasoline or fuel tax credits or refunds
Biofuel credit claimed on Line 3 of Form 6478
Biodiesel credit claimed on Line 10 of Form 8864
Line 7: Gross income
Add Line 5 and 6 together to get gross income.
Part II: Expenses
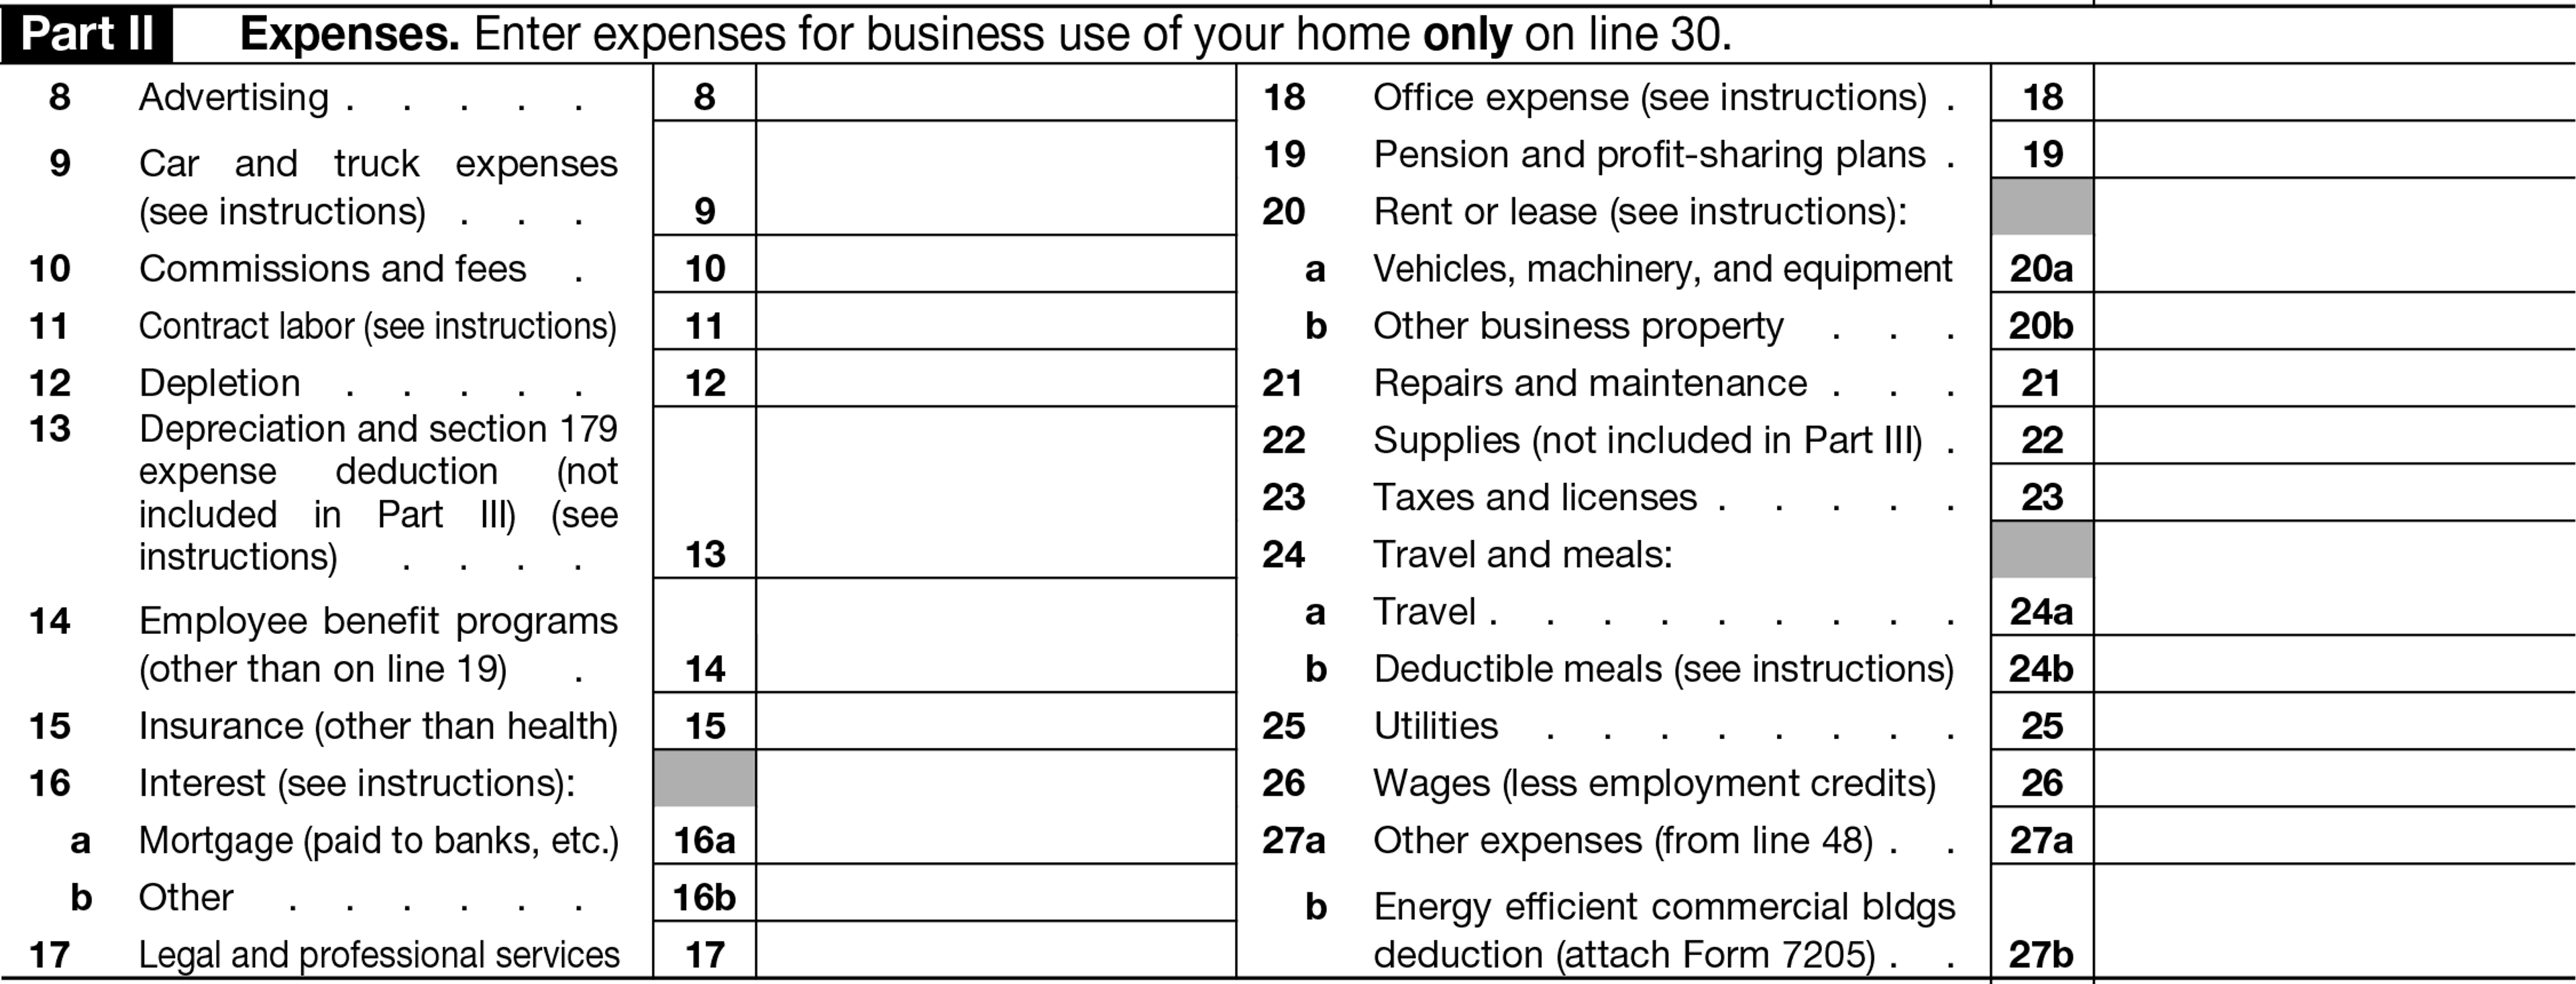
Here you’ll add up all of your business expenses.
Line 8: Advertising
Record any advertising-related expenses here. This might include print advertising fees, classifieds, promotional inserts, online ads, coupons, and any other expenses related to promoting your business online, on television or in print media.
Line 9: Car and truck expenses
Businesses have two options when reporting vehicle expenses: the Actual Expenses method and the Standard Mileage Rate (SMR).
The actual expenses method involves totaling up all of the costs involved in owning and operating a vehicle (like oil, gas, repairs, tires, insurance, license, registration fees and depreciation) and multiplying that number by the total percentage for business use to figure your deduction.
Under the standard mileage rate method, instead of adding up expenses, you simply multiply the total number of miles driven for business purposes by the Standard Mileage. For 2026, the IRS changed the rate partway through the year, so you’ll use two rates:
72.5 cents per mile for business miles driven January 1 through June 30, 2026
76 cents per mile for business miles driven July 1 through December 31, 2026
Note that in the first year you used your vehicle for business, you have to follow the standard mileage rate method if you’d like to keep both options open in the future. If you use the actual expenses method in a vehicle’s first year, you can’t switch to using the standard mileage rate going forward.
Line 10: Commissions and fees
Enter total commissions and fees you paid over the course of the tax year. Remember that you’ll probably also have to file Form 1099-NEC to report commissions and fees you paid if they totaled $2,000 or more.
Keep in mind that unless you’re a dealer who regularly sells property in the ordinary course of their trade or business, you might have to capitalize commissions and fees paid to facilitate the sale of property.
Line 11: Contract labor
Record your total non-employee contract labor costs for the year, and remember to file Form 1099-NEC for any payments of $2,000 or more for the year.
Exclude any contract labor you’re including elsewhere on the return, including legal services (Line 17), repairs and maintenance (Line 21) and cost of labor (Line 37).
If you’re not sure whether someone counts as a contractor or an employee, review our guide to 1099 vs. W-2 workers.
Line 12: Depletion
Depletion is the using up of natural resources by mining, quarrying, drilling, or cutting. For more on calculating depletion for a mineral property or standing timber, consult the “Depletion” section of Publication 225, Farmer’s Tax Guide.
Line 13: Depreciation and Section 179
Expenses that benefit your business for more than one year like machinery, equipment and buildings must usually be ‘depreciated’ or spread out and deducted over multiple years instead.
Before depreciating their expenses, many businesses will also take advantage of Section 179, which allows them to deduct some or all of the cost of assets in the first year that they’re placed in service, up to a limit of $2,560,000 in 2026. The limit starts to phase out once you place more than $4,090,000 of qualifying property in service during the year. Your Section 179 deduction also can’t be more than your business income for the year, though you can carry any excess forward.
Additionally, bonus depreciation lets you deduct 100% of the cost of qualifying property acquired after January 19, 2025. Unlike Section 179, bonus depreciation can create a loss.
Enter total depreciation and Section 179 deductions for the year on this line. If you’re claiming depreciation or a Section 179 expense deduction, you must also complete and attach Form 4562.
Line 14: Employee benefit programs
Enter any contributions to employee benefit plans you made, other than contributions to pension and profit-sharing plans you made (and reported on Line 19 of Schedule C). Examples might include:
accident and health plans
group term life insurance
dependent care assistance programs
Remember to complete Form 2441, Parts I and III if you contributed on your behalf as a self-employed person to a dependent care assistance program. Don’t include contributions you made on your behalf as a self-employed person for group-term life insurance or to an accident and health plan.
Reduce the amount on Line 14 for any credit for small employer health insurance premiums determined on Form 8941.
Line 15: Business insurance premiums
Enter any premiums you paid for business insurance. Don’t include any amounts paid for employee accident or health insurance–include those on Line 14 above instead.
Lines 16a and 16b: Interest
If you receive a Form 1098 for mortgage interest you paid on business property, report that mortgage interest amount on Line 16a. Enter any other business interest you paid on Line 16b.
If you have average annual gross receipts of more than $32 million and aren’t considered a “small business taxpayer,” you might have to file Form 8990 to deduct any interest expenses related to your business.
Line 17: Legal and professional services
Enter any fees you paid to accountants or attorneys for services related to your business like business incorporation, contract negotiation, tax preparation and advice, and tax deficiency resolution.
Line 18: Office expense
Enter any office supplies (i.e., paper, labels, ink and toner, organizers, shipping and packaging supplies, business cards and stationery) and postage expenses here.
Line 19: Pension and profit-sharing plans
Enter any contributions you made for your employees to pension plans, profit sharing plans or annuity plans. Don’t include any employer contributions (i.e., contributions for yourself as a self-employed person) here. Record those on Line 16 of Schedule 1 instead.
Line 20a and 20b: Rent or lease
Enter any business-related rental costs for vehicles, machinery, and equipment on Line 20a, and any other business-related rent payments you made (for commercial office or retail space, for example) on Line 20b.
Line 21: Repairs and maintenance
Enter any business-related repairs and maintenance costs like labor, supplies, tools and contractor fees. Do not include any expenses that ‘improve,’ ‘better,’ or ‘restore’ property in some way, and don’t include the value of your own labor.
Line 22: Supplies
Enter the cost of any supplies you consumed and used in the course of your business, excluding those you reported in the Part III COGS calculation.
This can include the cost of books, professional instruments, equipment, etc., if you normally use them within a year, but if their usefulness extends beyond a year you must depreciate them.
Line 23: Taxes and licenses
Record any business-related taxes or license fees you paid, including:
State and local sales taxes
Real estate and personal property taxes on business assets
Licenses and regulatory fees
Social security and Medicare taxes paid to match required withholding from your employees’ wages (reduced by the Form 8846, Line 4 amount)
Federal unemployment tax
Federal highway use tax
Contributions to a state unemployment insurance fund or disability benefit fund if they are considered taxes under state law
Don’t include any taxes you paid on your home or personal property, federal income or self-employment taxes, or other taxes and license fees not related to your business. Remember that you can deduct half of your self-employment taxes on Line 15 of Schedule 1.
Line 24a and 24b: Travel and meals
Enter any “ordinary” (common and accepted in your industry) and “necessary” (it helps develop or maintain your business in some way) lodging and transportation expenses incurred while traveling on Line 24a.
Only include expenses related to overnight travel away from home. Do not include entertainment expenses, or expenses for any other individual unless they’re an employee and the travel has a real business purpose.
Similar rules apply to business meal expenses. You can either include 50% of meal expenses, or 50% of a standard meal allowance. Meal expenses can include food, beverages, taxes, and tips. Do not include entertainment expenses, or any lavish or extravagant meal expenses. If you’re subject to the Department of Transportation’s hours-of-service rules (like many truck drivers), you can deduct 80% of your meal costs while traveling away from home instead of 50%.
Line 25: Utilities
Include telephone, internet, cell phone, and other utility expenses, but only the portion you use for business. Don’t include the cost of the first telephone line in your home, however you may include a second line used exclusively for business.
Line 26: Salaries and wages
Enter total salaries and wages paid to employees for the tax year. Reduce this amount by the following credits, if you claimed them:
Work Opportunity Credit (Form 5884).
Empowerment Zone Employment Credit (Form 8844).
Credit for Employer Differential Wage Payments (Form 8932).
Employer Credit for Paid Family and Medical Leave (Form 8994).
Line 27a and 27b
Enter total other expenses calculated on Line 48 in Part V on Line 27a.
If you claim part or all of the expenses of modifying an existing commercial building to make it energy efficient, record that amount on Line 27b and attach Form 7205. Note that this deduction (which is claimed under Section 179D) doesn’t apply to properties where construction started after June 30, 2026.
Line 28 and 29
Add all of the lines in Part II up until this point (Line 8 - Line 27b) to calculate total expenses before expenses for business use of home and enter that amount on Line 28.
Subtract the amount on Line 28 from the gross income figure on Line 7 to calculate tentative profit or loss and enter on Line 29.
Line 30: Expenses for business use of your home
Enter your business use of home expenses here. You have two options here: the actual expenses method and the simplified method.
Under the actual expenses method, you can deduct expenses directly associated with running and maintaining the office. Complete and attach Form 8829 if you use this method and enter the resulting amount on Line 30.
Under the simplified method, you multiply the total area of the home office in square feet by the prescribed rate from Publication 587, which is currently $5 per square foot (up to 300 square feet).
If you use the simplified method, enter the total square footage of your home and office in the fields provided, complete the simplified method worksheet in the instructions to Schedule C, and enter the resulting amount on Line 30.
Line 31: Net profit (or loss)
Subtract Line 30 from Line 29 to calculate net profit or loss for the business.
Enter any resulting profit on Line 3 of Schedule 1 (Form 1040), Line 2 of Schedule SE, and Line 3 of Form 1041 if your business is an estate or trust. Your net profit might also qualify for the qualified business income (QBI) deduction on Form 8995.
Line 32
If Line 31 shows a loss, check Box 32a or 32b to indicate how much of your investment in the business is at risk, i.e., how much of the loss is coming out of your own pocket.
Check Box 32b if there’s money invested in the business for which you are not at risk, including:
Nonrecourse loans, i.e., loans that only allow the lender to pursue the collateral
Borrowed amounts that are protected against loss by a guarantee, stop-loss agreement, or other similar arrangement, excluding casualty insurance and insurance against tort liability
Funds borrowed from a related person or a person who has an interest in the business
If you check Box 32b, complete Form 6198 to determine the extent of the losses you can claim on Schedule C.
Part III: Cost of Goods Sold
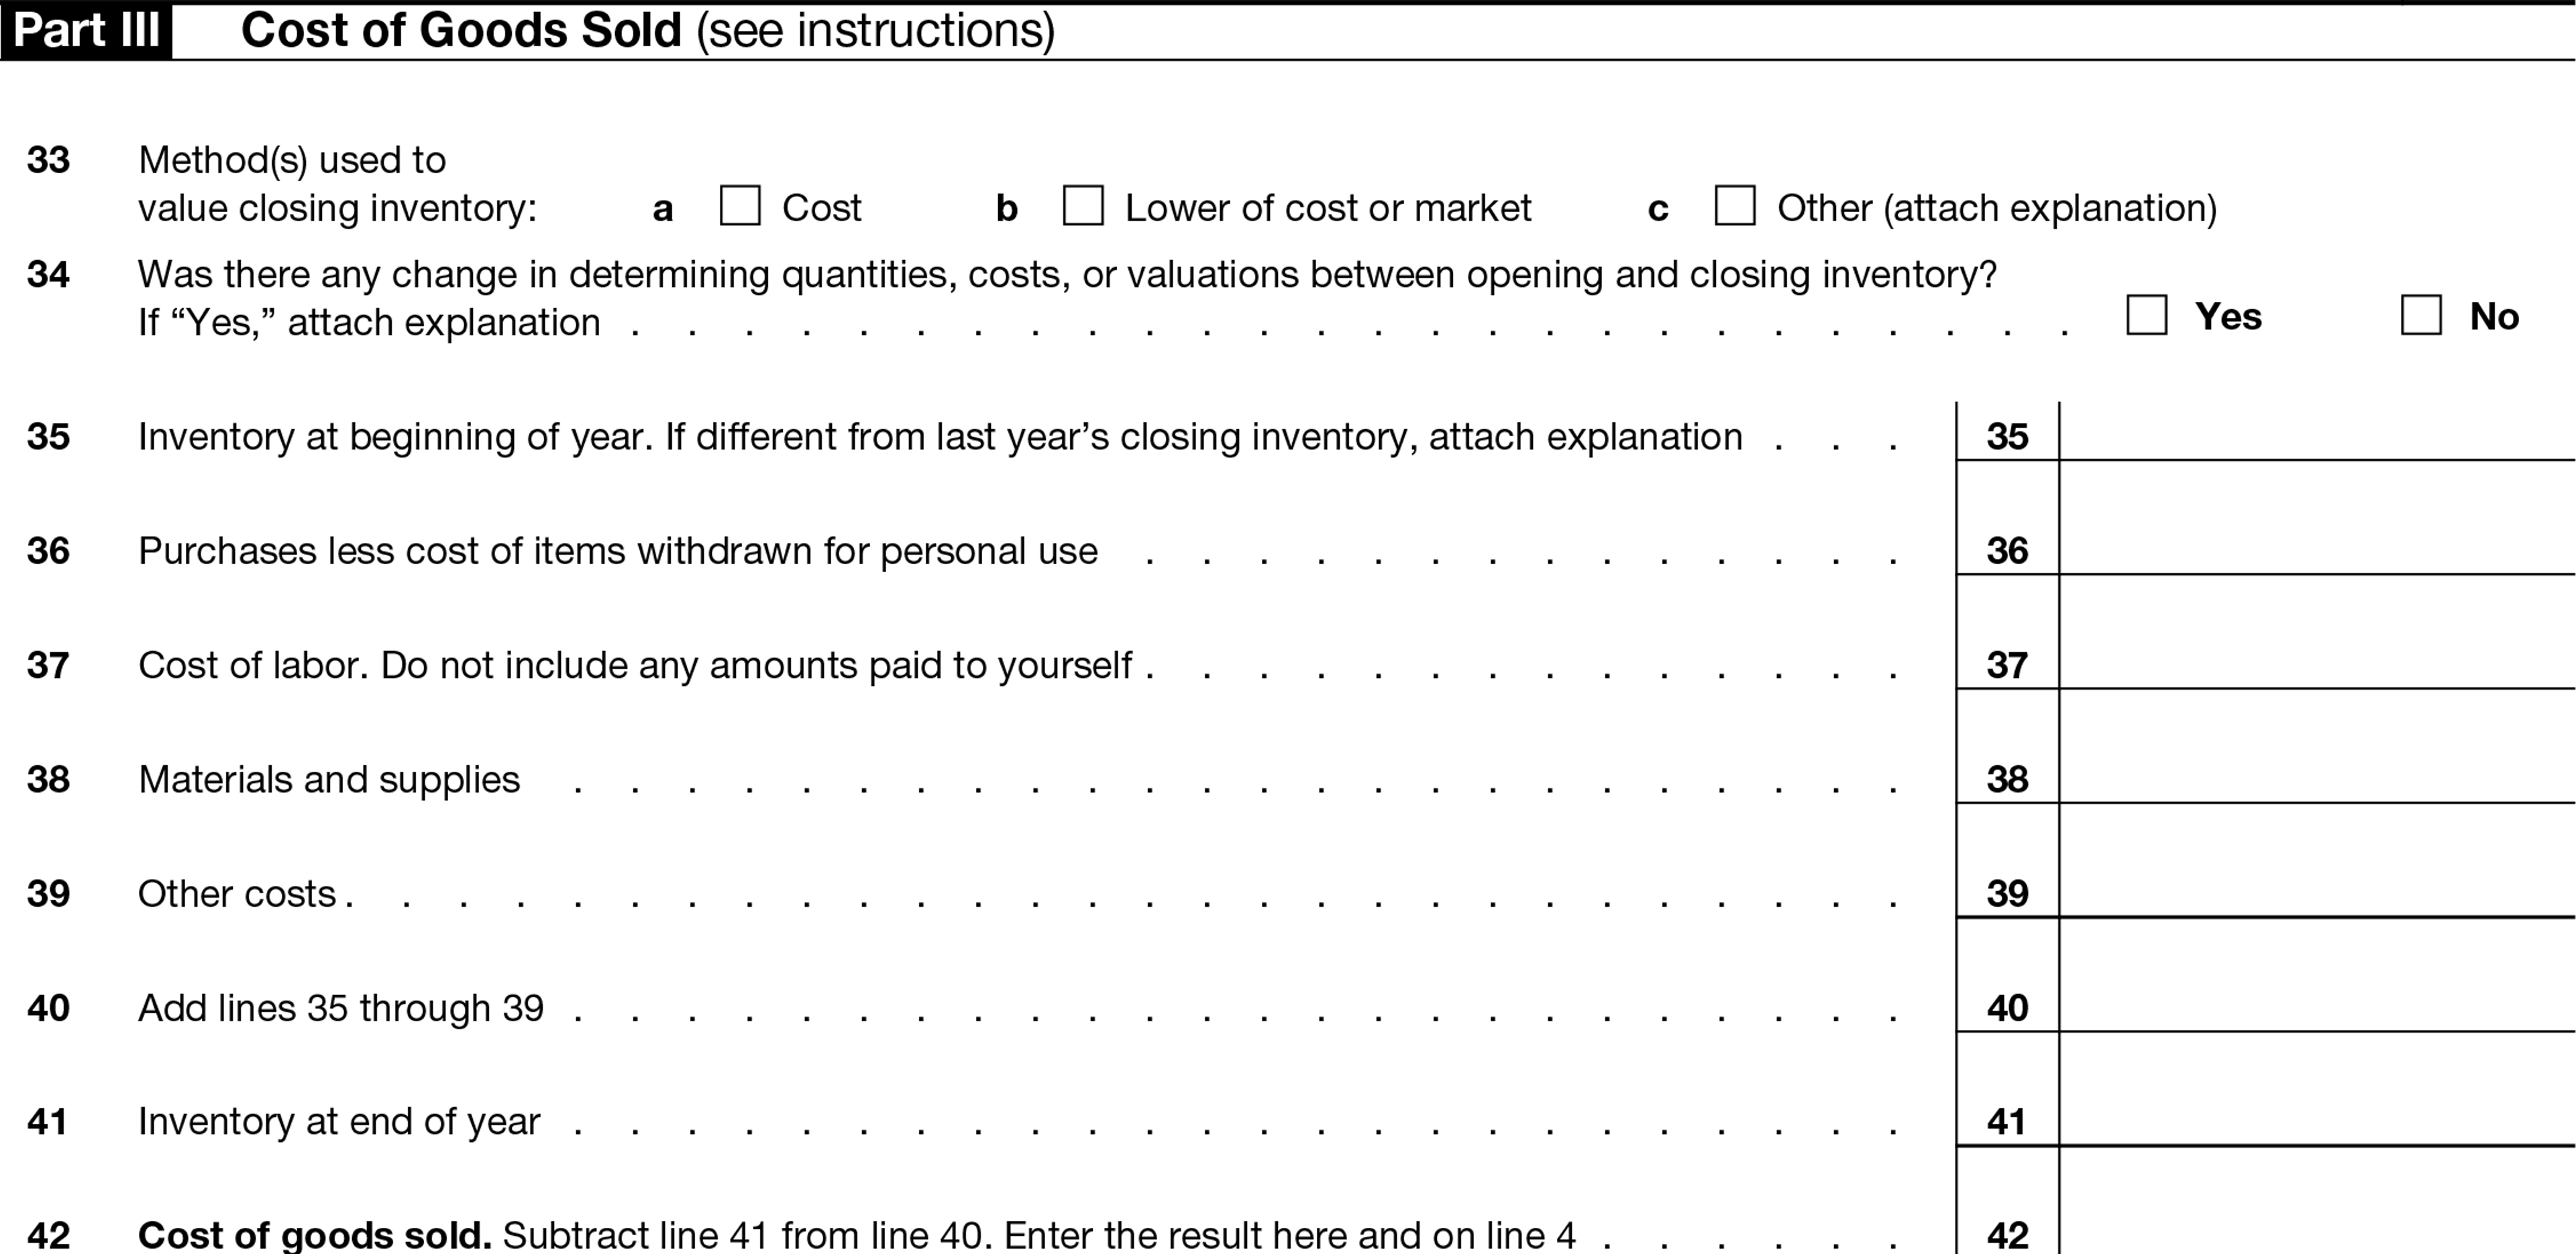
If your business manufactures or purchases goods for resale, you can deduct some of the expenses involved in the Cost of Goods Sold section.
Line 33: Method(s) used to value closing inventory
Use the boxes here to indicate the method you use to value your inventory: cost, lower of cost or market, or other.
If you use the cash method of accounting, you probably use the cost method, which uses the original purchase cost to value inventory.
The lower of cost or market (LCM) method uses either the original purchase cost, or the fair market value of the inventory, whichever one is lower.
If you use another method, check the “other” box and attach an explanation to Schedule C. For a side-by-side comparison of the options, check out our guide to inventory valuation methods.
Line 34
If at any point during the year you changed the method by which you determined inventory quantities, costs, or valuations, check the “Yes” box and attach an explanation.
Line 35: Inventory at beginning of year
Enter the opening inventory at the beginning of the tax year. If this amount is different than the closing inventory reported for the tax year preceding, attach an explanation.
Line 36: Purchases less cost of items withdrawn for personal use
Enter your total purchases for the tax year, minus the cost of any items withdrawn for non-business use.
Line 37-39: Cost of labor, materials, supplies, and other costs
Using information from your income statement, enter the cost of labor (Line 37), materials and supplies (Line 38) and other costs (Line 39) for the tax year.
Line 40
Add lines 35 through 39.
Line 41: Inventory at end of year
Enter your closing inventory for the end of the tax year.
Line 42: Cost of goods sold
Subtract Line 41 from Line 40 to get the total cost of goods sold for the tax year. Record the amount here and on Line 4.
Part IV: Information on Your Vehicle
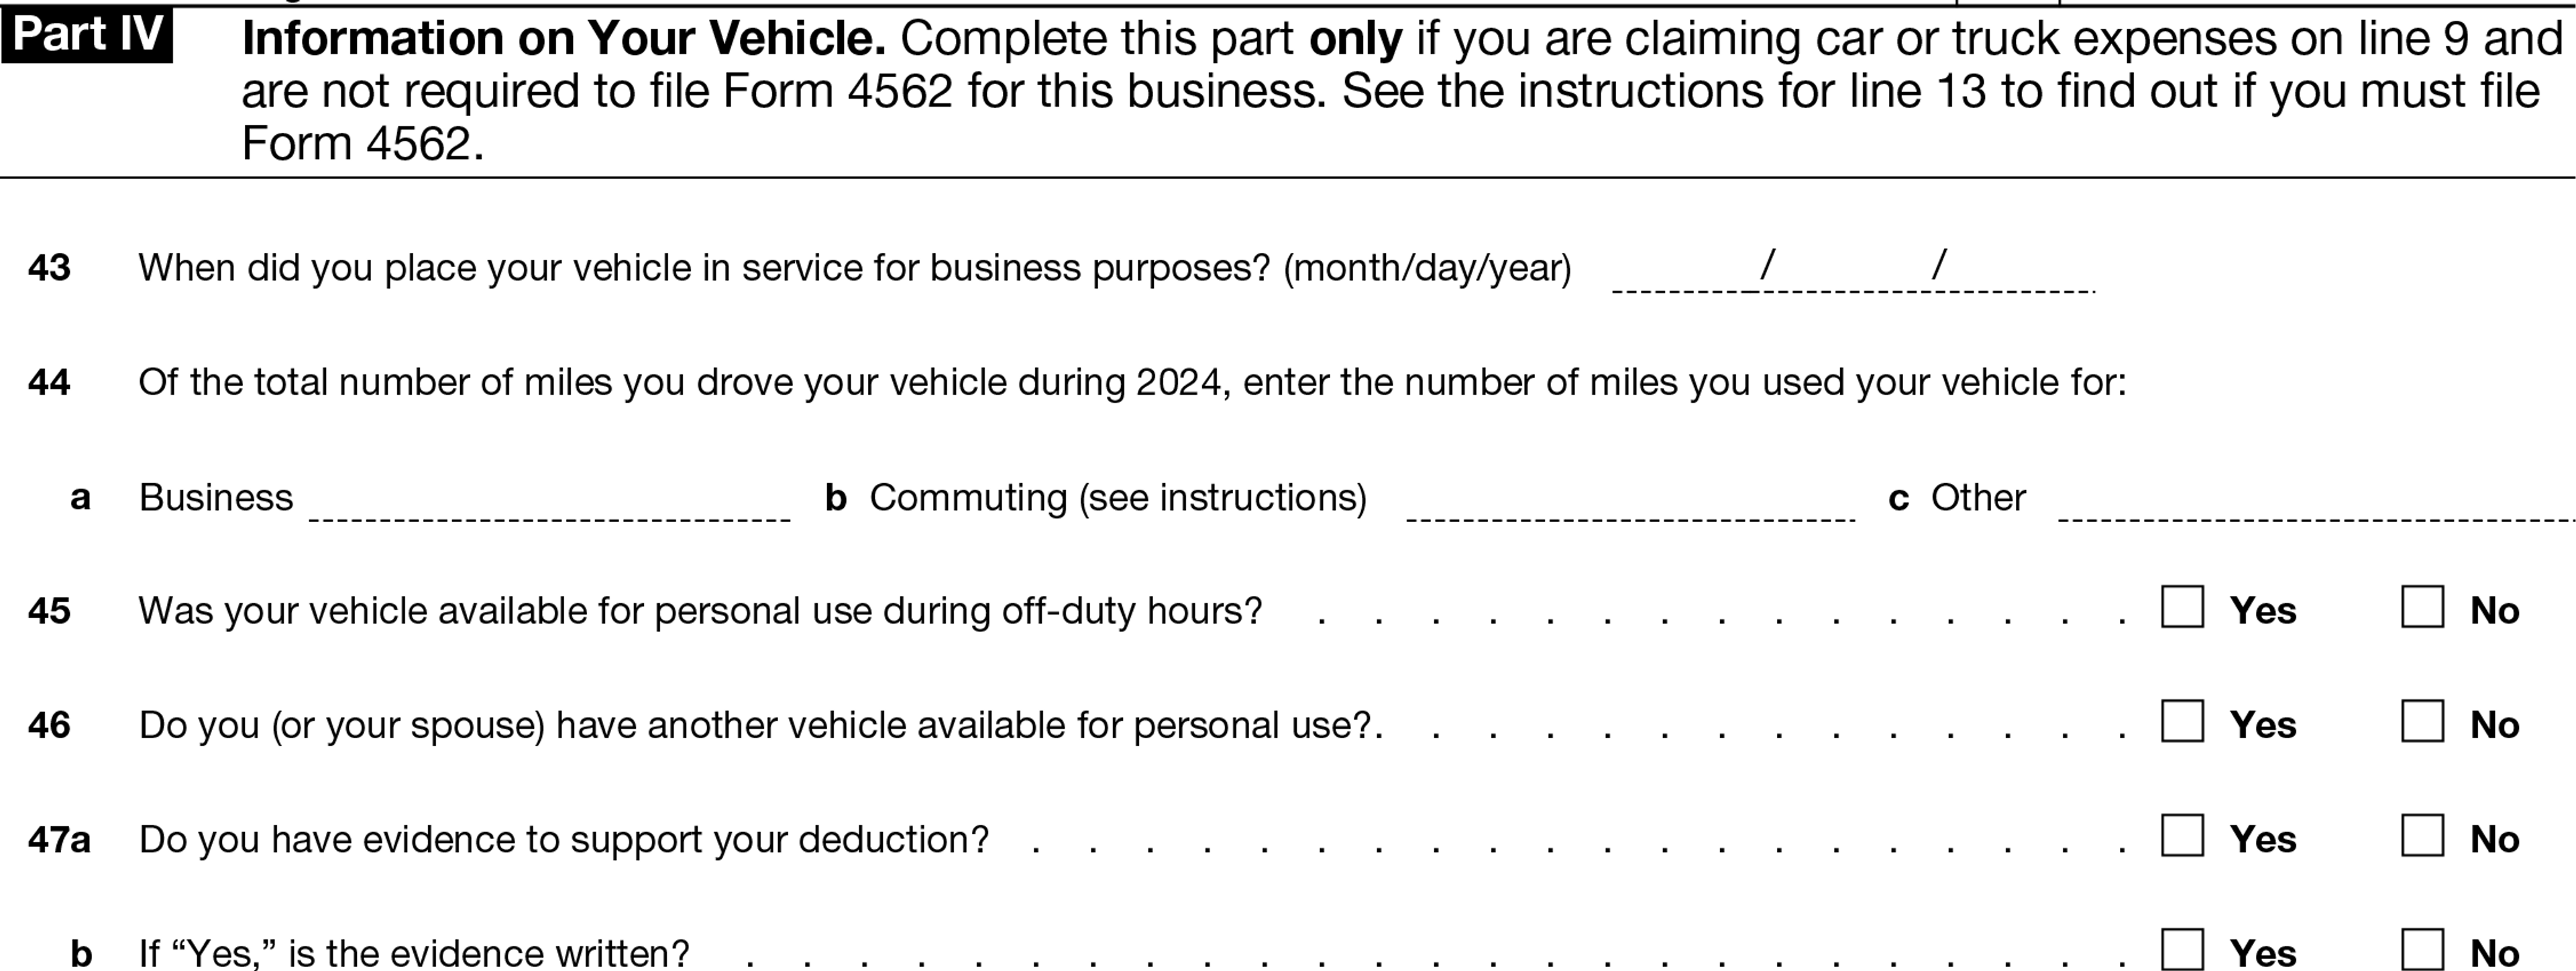
You only have to complete this section if you’re claiming vehicle expenses on Line 9 and aren’t required to file Form 4562. (You must file Form 4562 if you’re claiming depreciation or a Section 179 expense deduction.)
If you aren’t claiming vehicle expenses on Line 9 or you are required to file Form 4562, skip ahead to Part V.
Line 43
Enter the date you placed your vehicle in service.
Line 44
Using information from your mileage log, enter the total number of miles you drove your vehicle for business (Line 44a), commuting (Line 44b) and other purposes (Line 44c).
Line 45
Note whether your vehicle was available for personal use during off-duty hours.
Line 46
Note whether you (or your spouse) had another vehicle available for personal use.
Line 47a and 47b
Note whether you have written evidence to support your vehicle deduction. Written evidence for business mileage usually comes from a timely and accurate mileage log. (Check out our guide to keeping a vehicle mileage log for more information.)
Part V: Other Expenses
Use this section to list any business expenses not mentioned elsewhere on Schedule C, including:
Amortization for goodwill and certain other intangibles, research and experimentation, and amounts paid to acquire trademarks
Losses from the business that were not allowed last year because of the at-risk rules
Debts and partial debts from sales or services that were included in income and are definitely known to be worthless
De minimis safe harbor for tangible property
Consult the instructions to Schedule C for a full list of expenses that you can include in Part V. Do not include the cost of business equipment or furniture, replacements or permanent improvements to property, or personal, living, and family expenses on Part V.
Frequently asked questions (FAQs) about Schedule C
Now that we’ve gone line by line through the form, let’s review the most common questions about Schedule C one more time.
What is Schedule C?
If you operate as a sole proprietor or a single-member LLC, Schedule C (Form 1040) is the IRS form you’ll use to report your business’s profit or loss. The net profit gets added to any other income you have and is subject to self-employment tax.
Who has to file Schedule C?
Anyone who runs a business as a sole proprietor, including single-member LLCs that haven’t elected to file as corporations, independent contractors, and statutory employees. You’re automatically considered a sole proprietor by the IRS if you regularly work for profit and haven’t formed a partnership or corporation.
Do I have to file Schedule C if I made less than $400?
Yes. You report all business income on Schedule C, even if it was less than $400. That $400 figure is the threshold for owing self-employment tax on Schedule SE.
Can I file both Schedule C and Schedule F?
Yes, in fact many agricultural producers will end up filing both. The difference between them is that farm income goes on Schedule F, while non-farm business income goes on Schedule C (e.g., agritourism, sales from processed products, or any non-farm contracting work you might have taken on). Don’t report the same income or expense on both forms.
Do I need to file separate Schedule C for each business?
Yes. If you run two different businesses, like a framing business and a freelance design business, you’ll need to file a separate Schedule C for each one.
What’s the difference between Schedule C and Schedule SE?
Schedule C calculates your business profit, while Schedule SE takes that profit and calculates your self-employment tax.
When is Schedule C due?
Together with your Form 1040, Schedule C is due on April 15. (If April 15 falls on a weekend, the deadline will move to the next business day.)
Simplify your tax planning with Ambrook
In Ambrook, categories are mapped directly to lines on Schedule C. The software automatically keeps track of relevant income and expenses as you tag transactions throughout the year, so you save hours of work on piecing things together at tax time.
Once it’s time to file, export a Schedule C breakdown in one click and hand it over to your accountant with everything prepared.
Still looking for support with your taxes? Ambrook Tax pairs you with a tax pro who helps you plan and file right from your books. Book a free intro call to learn more.
This resource is provided for general informational purposes only. It does not constitute professional tax, legal, or accounting advice. The information may not apply to your specific situation. Please consult with a qualified tax professional regarding your individual circumstances before making any tax-related decisions.