
If you paid a freelancer, contractor, or other non-employee $2,000 or more for the year, you might have to file a 1099-NEC. Here’s how to know for sure and prepare ahead of tax season.
If you pay someone who isn’t your employee (like a freelancer or independent contractor) $2,000 or more over the course of the calendar year, you’ll probably have to file Form 1099-NEC to report those payments to the IRS.
And if you’re the one doing work for another business as a non-employee, you might find yourself receiving 1099-NECs in the mail and having to report that income on your tax return. Let’s break down what Form 1099-NEC is, how to know if you need to file one, and important deadlines you should keep an eye on.
Key takeaways
Businesses use Form 1099-NEC to report payments of $2,000 or more to a non-employee worker in a single year. That minimum payment threshold was raised from $600, starting with payments in 2026.
You need to file 1099-NEC with the IRS and send a copy to the recipient (the worker you paid) by January 31.
You don’t need to issue a 1099-NEC for contractors you paid by credit card or a payment app. Those payments will be reported on Form 1099-K by the relevant financial institution.
If you paid a business taxed as a C corporation or an S corporation, those payments usually don’t get reported on a 1099-NEC.
There are IRS penalties for late 1099-NEC filings, ranging from $60 to $340 per form.
What is Form 1099-NEC?
IRS Form 1099-NEC is a tax form businesses file to report payments to non-employee workers, like subcontractors or freelancers. Starting in 2026, you’ll file a 1099-NEC for any worker you paid $2,000 or more over the course of the year. (See more on payment thresholds below.)
For example as a producer, you might file Form 1099-NEC for someone you hired to apply pesticides to your crops or repair your cattle fences. If you run a construction business, maybe you’ll file it for the framing and roofing subs you worked with this year. And besides filing it with the IRS, you’ll also need to send a copy of the form (Copy B) to the person you paid, also called the “recipient” or the “payee.”
On the flip side, that means if you did custom work for another business like repairs, improvements, farm labor, consulting services, and so on, you might get copies of Form 1099-NEC in the mail from your clients. You’ll then use those copies to help you fill out the following forms and report income on your own return:
Schedule F (Form 1040) for farming income
Schedule C (Form 1040) for other business income
Schedule SE (Form 1040) for self-employment tax
Form 8995 for qualified business income deduction

In Tennessee, Kevin uses Ambrook to run the books for Double V Ranch.
Who gets a 1099-NEC, and who doesn’t?
Here’s how to know whether you actually need to file a 1099-NEC for someone or not. In general, you’ll file a 1099-NEC for a worker you paid if all of the following is true:
They are not your employee. (In the next section, we’ll cover what makes someone an employee or a non-employee worker.)
You paid them for business services, not for personal reasons.
They’re an individual, a partnership, or an estate. Or, they’re a corporation you paid for legal services.
You paid them $2,000 or more during the year.
On the other hand, you usually won’t need to file a 1099-NEC for:
Payments to C corporations or S corporations, including LLCs that are taxed as corporations. (The main exception is legal services: If you paid attorney’s fees to a corporation, you do need to report them on 1099-NEC.)
Payments made by credit card, debit card, or a third-party payment network like PayPal or Venmo. In these cases, the card company or payment processor is responsible for reporting payments on Form 1099-K.
Payments for merchandise, freight, storage and similar items.
Wages, bonuses and prizes paid to employees, which go on Form W-2.
Payments to tax-exempt organizations and government agencies.
If you want to confirm whether certain payments you made need to go on a Form 1099-NEC, check the IRS’s instructions and ask your accountant for clarification.
Example: Which vendors get a 1099-NEC?
Say you run a cattle operation, and you’ve paid three vendors in 2026. Here’s why each one would or wouldn’t get a 1099-NEC:
| Vendor | Operates as | Amount you paid them this year | Do you need to file a 1099-NEC? | Explanation |
|---|---|---|---|---|
| Fencing contractor | Single-member LLC (disregarded entity; owner files as a sole proprietor) | $4,800 | Yes | The contractor’s an individual who you paid $2,000 or more for services this year. |
| Equipment repair shop | S corporation | $3,500 | No | Even though you paid the shop for repair services, they’re a corporation, so you don’t need to file Form 1099-NEC. |
| Feed supplier | Sole proprietor | $8,000 | No | Feed is merchandise, not services, so you don’t need to file 1099-NEC. |
This simple example illustrates what we covered so far, but remember that if you’re researching your specific situation, you should always consult your accountant.
What’s the difference between an employee and an independent contractor?
An employee is a worker who contributes to your core business in some way, and according to the IRS, whose work you can direct and control. They’re also sometimes called a “Form W-2” employee, named after the IRS form you’re required to file for them.
In addition to paying them wages, hiring a W-2 employee comes with a long list of responsibilities. That includes filing or collecting Forms W-2, W-4, and I-9 for each one, withholding payroll taxes from their paychecks, and sometimes contributing to employee health insurance or workers’ compensation insurance.
An independent contractor (also sometimes called a “Form 1099” contractor) is different. Other than filing a Form 1099-NEC for each one you pay $2,000 or more, your relationship with an independent contractor comes with many fewer rules and stipulations.
At the same time, contractors are fundamentally different from employees. In the eyes of the government and the IRS, they’re self-employed individuals you go into business with, not employees whose hours you can set and work you can control. For more information, you can check out our guide to 1099 contractors vs. W-2 employees.
1099-NEC vs. MISC: What’s the difference?
Before 2020, taxpayers used 1099-MISC to report non-employee compensation, in addition to a broad range of other payments. That year the IRS (re)introduced an old tax form called Form 1099-NEC specifically for reporting payments to non-employees.
Form 1099-MISC is now mainly used to report rents, royalties, veterinary fees, crop insurance proceeds, prizes, awards, gross proceeds to attorneys (like legal settlements), medical and health care payments, and a range of other miscellaneous business payments that aren’t reportable using the other 1099 forms.
Here’s a quick overview of how 1099-NEC and 1099-MISC are different:
| 1099-NEC | 1099-MISC | |
|---|---|---|
| What it reports | Payments for services from non-employees | Payments for expenses including (but not limited to) rents, royalties, crop insurance proceeds, medical and health care payments |
| Minimum payment threshold | $2,000 | $2,000 for most payment types. $10 for royalties, or $600 for gross proceeds to attorneys. |
| Deadline to file with the IRS | January 31 | February 28 if you’re filing on paper or March 31 if you file online |
| Deadline to send your recipient a copy | January 31 | January 31 |
What’s the 1099-NEC reporting threshold for 2026?
Up to 2025, the threshold for filing a 1099-NEC was $600. But for payments made in 2026, the reporting threshold for 1099-NEC was raised to $2,000. It’ll be adjusted for inflation for 2027 and beyond.
This means any payments you’ve made in 2026 are subject to the new $2,000 threshold, and thresholds may change with inflation for 2027 and beyond.
What do I need before filling out and filing 1099-NEC?
In addition to information about the payment type and amount, you’ll need the recipient’s name, contact information and taxpayer identification number (TIN) to properly file a 1099-NEC. You can get this information by giving them a copy of Form W-9. We’ve written a guide to Form W-9 that covers when and how to request one in more detail.
If the recipient doesn’t get back to you with a filled out W-9 and TIN, you’ll have to withhold taxes from their payment at the backup withholding rate of 24%. (More on that below.)
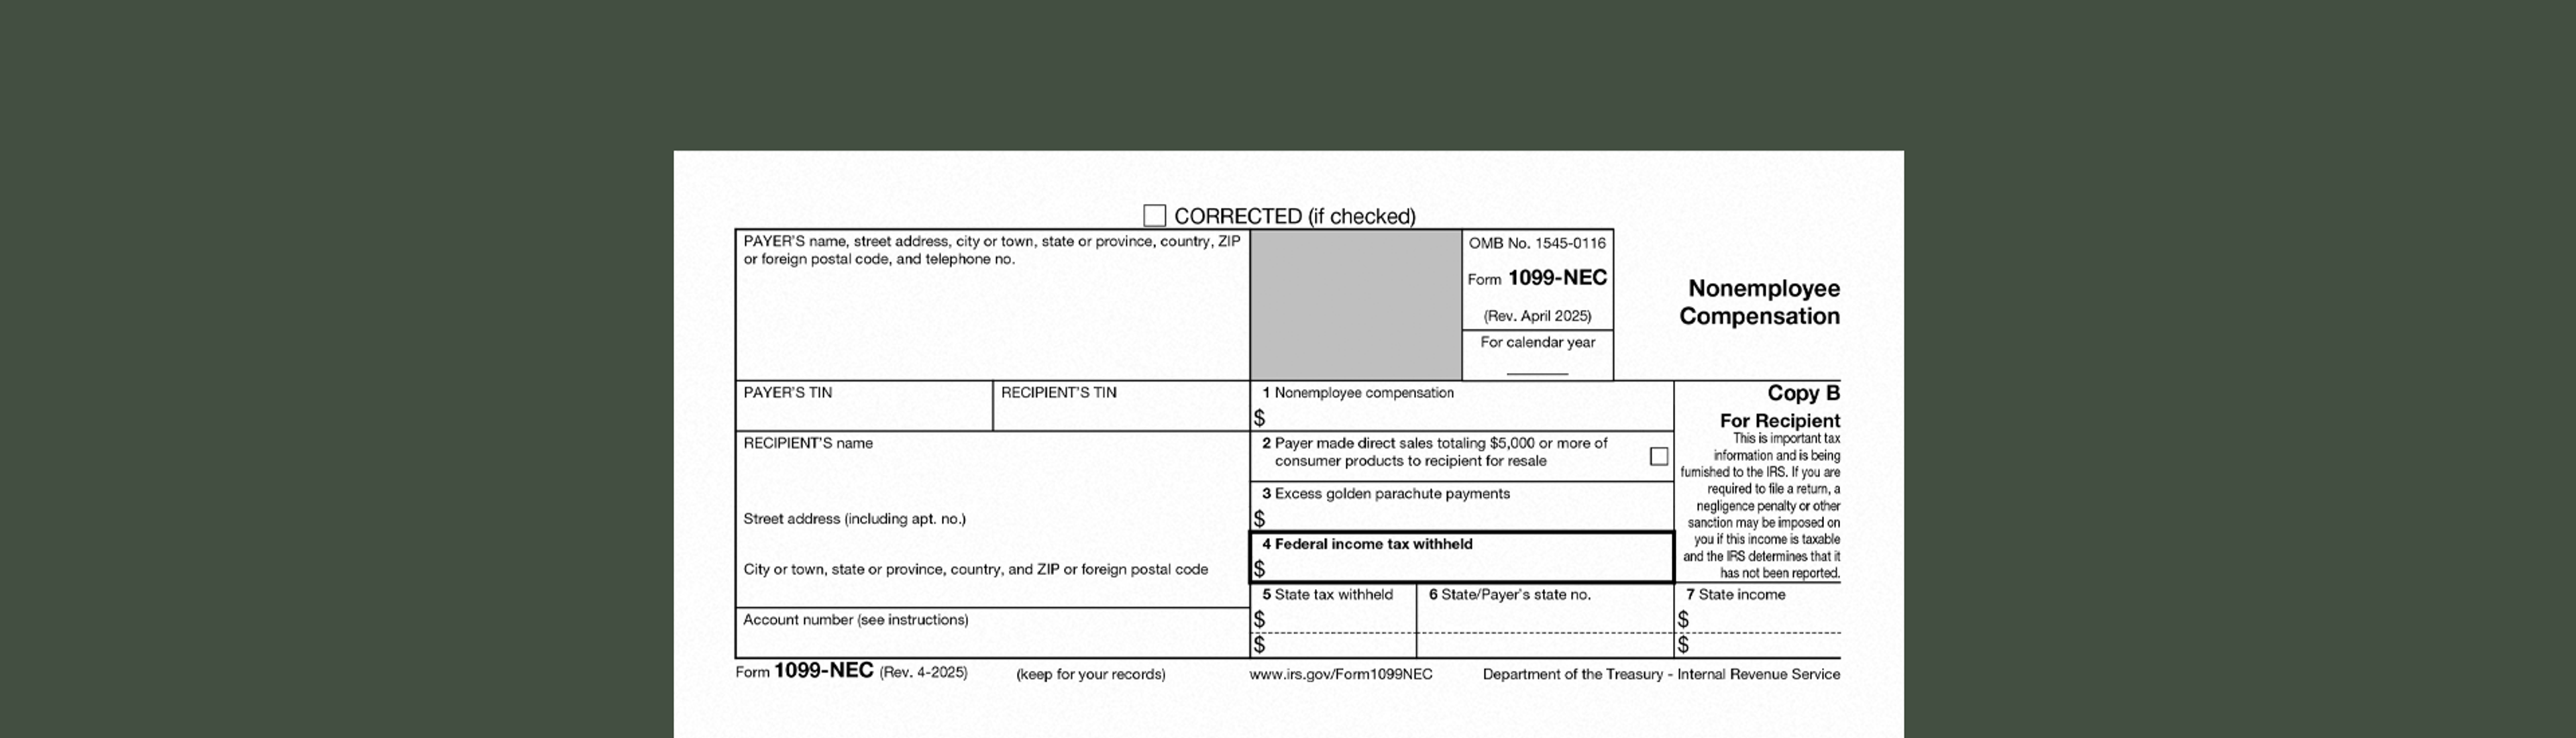
Form 1099-NEC: a box-by-box breakdown
On the left hand side of 1099-NEC, enter the payer’s (your) name and contact information, your taxpayer identification number (TIN), your recipient’s TIN, and the recipient’s name and contact information.
If you’re filing more than one information form for each recipient, include an account number at the bottom of the form. This can be a checking account number, savings account number, brokerage account number, serial number, loan number, policy number, or any other unique number you assign that payee to distinguish their account.
Box 1a: Nonemployee compensation
This box should include total nonemployee compensation paid to the recipient, and can include payments like:
Professional service fees, such as fees to attorneys, accountants, engineers and consultants
Payment for services like property repairs and maintenance, including payment for parts or materials when the parts or materials are incidental to the service
Commissions paid to nonemployee salespersons
Any fees paid to independent contractors
Services you traded with another business, at their fair market value
Do not include payments reportable on other 1099 forms, including:
Rents (1099-MISC)
Prizes and awards, including certain non-government grants (1099-MISC)
Medical and health care payments (1099-MISC)
Crop insurance proceeds (1099-MISC)
Payments from the government (1099-G)
Patronage dividends from cooperatives (1099-PATR)
Gross proceeds paid to attorneys, like settlements (1099-MISC)
If you receive a copy of 1099-NEC, you’ll have to report this amount on Schedule F (Form 1040) or Schedule C (Form 1040), depending on whether it qualifies as farming income.
Boxes 1b-1d: Cash tips, tipped occupation code, and overtime
These boxes are new for 2026. Box 1b shows cash tips, box 1c is for the IRS’s three-digit tips classification code, while box 1d shows qualified overtime pay. These amounts are included in the total recorded in box 1a. You can leave these blank if you didn’t pay tips or overtime to the recipient.
Box 2: Direct sales
Check this box if you (the payer) made $5,000 or more in sales to the recipient on a buy-sell, deposit-commission, or other commission basis for resale (i.e., ‘direct sales’). You may also use box 7 on Form 1099-MISC to report this, however you must only use one form.
Box 3: Excess golden parachute payments
This box is for certain contractor payments related to a corporation changing ownership or control. These payments used to be reported on 1099-MISC, and aren’t relevant for most small businesses.
Box 4: Federal income tax withheld
This box is used to report backup withholding. If you’re the payer and the recipient hasn’t furnished you with their TIN, you must withhold tax from their payments and file Form 945 to report it. The current backup withholding rate is 24%.
If you receive a copy of 1099-NEC with an amount in this box, the payer withheld tax because they didn’t have your correct TIN. Send them a completed Form W-9 as soon as you can to stop future withholdings.
Box 5-7: State information
These boxes contain any state income tax withheld from payments, the state and the payer’s state identification number, and the taxable income for the tax withheld.
At Bread & Butter Farm in Shelburne, Vermont.
How do I file Form 1099-NEC?
You have to file multiple copies of Form 1099-NEC, each one for a different recipient:
The first copy, “Copy A,” goes to the IRS and needs to be filed by January 31. That’s both for filing on paper and electronically.
The second copy, “Copy B,” goes to the recipient so they can report that income on their own taxes. It’s also due by January 31.
You might also have to file two other copies: “Copy 1,” which goes to your state or local tax department, and “Copy 2,” which goes to the recipient and can be filed with their state or local tax department if necessary. If you think you might need to file Copy 1 and Copy 2, check the IRS’s instructions for 1099-NEC and ask your accountant about it.
If you file your taxes on paper, you’ll also have to file Form 1096, which acts as a kind of cover sheet for all of your information returns. You don’t need to worry about Form 1096 if you’re filing online.
Filing your taxes electronically
You have to file your taxes electronically if you have 10 or more information returns in total. That includes all types combined, not just Forms 1099-NEC.
Note that there are a few options for e-filing: You could either use the IRS’s free Information Returns Intake System (IRIS) or one of the many third-party tax platforms out there.
Fixing a mistake on your 1099-NEC
If you notice an error after you’ve filed the 1099-NEC, you’ll need to file a corrected one with the IRS and send the recipient a new copy, either on paper or online. Here are a few common errors on Forms 1099-NEC and how to correct them:
Incorrect amounts: File a new 1099-NEC, enter the right numbers, and check the CORRECTED box.
Incorrect name or TIN: You’ll need to file two new versions of the form.
First, file a version where you check the CORRECTED box, enter the payee’s information as it was on the incorrect form, but enter all amounts as $0.
Then, file a second version with the right amounts and payee information. Do not check the CORRECTED box.
If you’re on paper, you’ll also have to send in a new Form 1096 with any corrections. Check the IRS’s instructions for more detailed steps on correcting a paper form.
When does each copy of 1099-NEC have to be sent out?
If you’re filing a 1099-NEC for payments you made, Copy A needs to get to the IRS by January 31 and Copy B should be sent to your recipient by the same date.
For any payments you received during the year, you should expect to get a copy of Form 1099-NEC by early February of the following year. (So if you were paid in 2026, expect to receive a copy of your 1099-NEC by February of 2027.) If you don’t, follow up with the payer about getting one issued.
For 1099 forms due in 2026, there’s currently a $60 late penalty per form if you file within 30 days of the deadline, which goes up to $130 between 30 days and August 1, then $340 if you file after August 1st, and at least $680 if you intentionally fail to file.
Summary of important deadlines for Form 1099-NEC
As we’ve covered so far, here’s a clearer snapshot of the dates to keep an eye on if you’re filing or receiving a Form 1099-NEC.
Form 1099-NEC deadlines:
| Milestone | Deadline |
|---|---|
| 1099-NEC, Copy A sent to the IRS | January 31* |
| 1099-NEC, Copy B sent to the recipient | January 31 |
*If January 31 falls on a weekend, the due date moves to the next business day. For example in 2027, January 31 is a Sunday, so the due date to file becomes Monday, February 1.
Late filing penalties in 2026:
| If you file a correct form… | Penalty per form |
|---|---|
| Up to 30 days late | $60 |
| 31 days late through August 1 | $130 |
| After August 1, or never filed | $340 |
| Intentional disregard | $680 or more, with no annual cap |
How to track 1099 payments in Ambrook
Filing 1099-NECs can get a lot easier if your accounting software helps you track relevant payments to vendors and contractors throughout the year.
For example in Ambrook, you can set up the system to automatically keep a running total of what you’ve paid contractors throughout the year. In short, here’s how it works:
If you expect to file a 1099 for a vendor, check the box in their contact for 1099 payments tracking.
Map expense categories to 1099 boxes, so transactions get counted toward the right box when you tag them.
At year-end, download the 1099 payments report and use it to help you file 1099-NEC.
Note that Ambrook doesn’t file your taxes for you, but you can export a tax breakdown and refer to them as you’re filling out 1099-NEC.
Simplify tax season with Ambrook
Ambrook can help you save hours on tax prep, by mapping your expenses categories directly to Schedule F, Schedule C, and 1099 boxes. If you work with an accountant, invite them to work directly in the books with you, so there’s no more back and forth on reports during the busy season. Or, if you’re still looking for support with tax prep, you can work with a licensed professional right in Ambrook.
Want to see how Ambrook works for your operation? Try it free for 30 days.
This resource is provided for general informational purposes only. It does not constitute professional tax, legal, or accounting advice. The information may not apply to your specific situation. Please consult with a qualified tax professional regarding your individual circumstances before making any tax-related decisions.