
A trial balance makes it easy to scan your books for mistakes before you close the month. Here’s how to prepare one and fix any errors it finds.
A trial balance is a report that lists the ending balance of every account in your books, with debits in one column and credits in the other. If the two columns add up to the same total, your books are in balance. If they don’t, there’s an error to track down. You can think of it as a “sanity check” for your bookkeeping.
If you have an accountant, they might ask you to bring them a trial balance each month so they can prepare financial statements for your operation. In general, it’s also a good idea to run a trial balance before you use software or spreadsheets to prepare your own financial statements or tax return.
Here’s everything you need to know about trial balances for your operation: how they work, how to prepare one, and how to spot errors.
Key takeaways
A trial balance adds up the ending balances of all your accounts at a given point in time, to check that total debits equal total credits.
If debits and credits don’t balance, it means there was a recording or calculation error in your books. This helps you find and fix those mistakes faster.
Many businesses run a trial balance monthly or quarterly, especially before preparing financial statements or handing the books over to an accountant.
A balanced trial balance alone doesn’t prove that your books are completely accurate. For example, it won’t catch a missing transaction or an entry booked to the wrong account.
What is a trial balance?
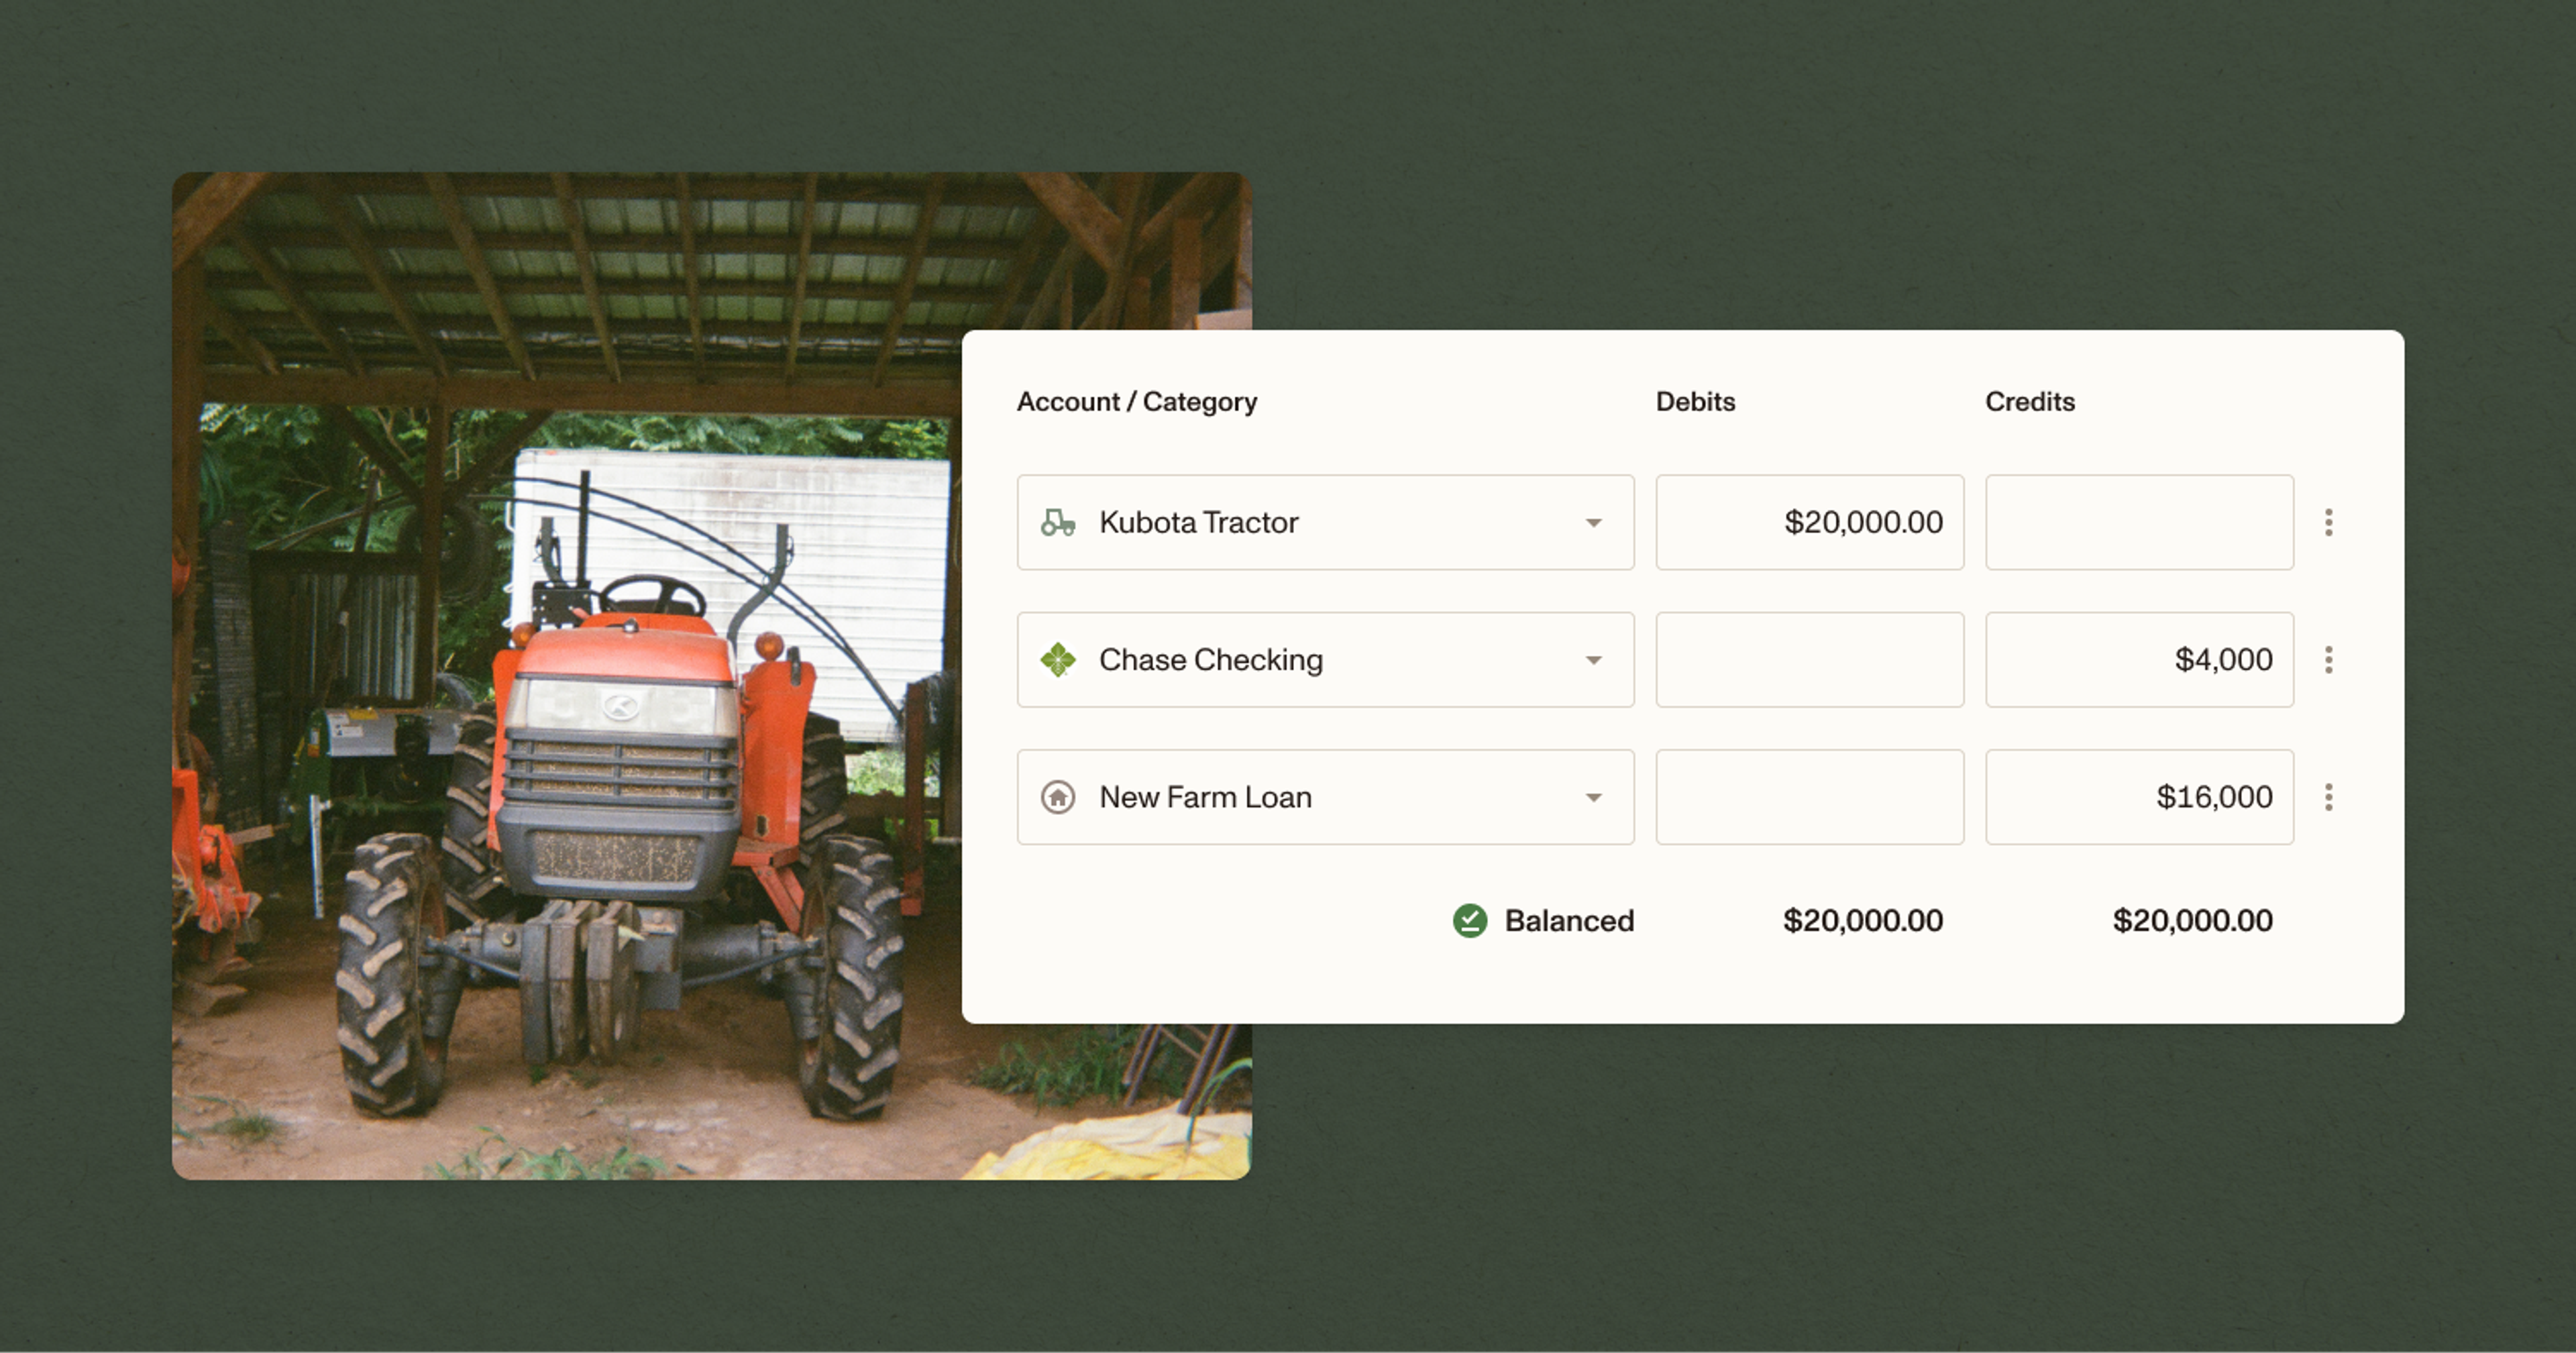
In double-entry bookkeeping, every transaction has two parts: a credit and a debit. For the amount of every debit, there is an equivalent amount in credit; for every credit, there is an equivalent amount in debit.
A trial balance adds up the credit and debit balances of every account in your books at a given point in time to make sure the totals match. If they do, that’s a good sign. If they don’t, you know there’s an error somewhere in your bookkeeping.
This makes it easy to scan your ending account balances for potential mistakes. For example, if you have a large credit balance in a cash account, either your bank account is overdrawn or there’s an error somewhere. If a loan balance is lower than expected, you might have allocated 100% of your payment to the principal balance instead of recording some of the payment as interest expense.
Regularly running a trial balance ensures the entries used to generate your financial statements are accurate, so your financial statements will be accurate, too. (And you need those to be accurate to properly file your taxes, plan your business’s finances, apply for loans, and do all sorts of other things.)
How often should you run a trial balance?
Many business owners who do their own bookkeeping run trial balances on an irregular basis.
That is, they might wait until a time when they’ve recorded lots of entries in their general ledger—for instance, at the beginning or end of the growing season, or after a busy stretch of jobs and projects is over—and then run a trial balance to make sure the numbers add up.
But it’s best practice to run trial balances and generate financial statements on a regular, recurring basis, ideally monthly or quarterly. That gives you better insight into how your operation is performing financially, and helps you catch errors sooner.
Also, if you apply for a loan from a bank, you will likely need to provide financial statements for your operation. You have a better chance of qualifying for a loan if your finances are organized, with regular trial balances and financial statements.

The Meyer family uses Ambrook to run the books for their diversified farm and seed supply, Meyer Seeds.
The trial balance vs. the balance sheet
A trial balance checks to make sure your books are accurate before you generate financial statements. A balance sheet is one of the financial statements you generate after running a trial balance.
The balance sheet lists all of your business’s assets, liabilities, and equity at a point in time. It’s an important tool for financial planning. For more, see How to Read a Balance Sheet.
| Trial Balance | Balance Sheet | |
|---|---|---|
| What is it? | Internal report to check that debits equal credits across your accounts, though you’ll often share it with your accountant too | Financial statement you share with lenders and your accountant |
| Which accounts are included? | Assets, liabilities, equity, income, expenses | Assets, liabilities, equity |
| When do you generate one? | Before preparing financial statements, and as a regular bookkeeping check | After running a trial balance, before applying for loans or other funding |
The trial balance and double-entry bookkeeping
When you use double-entry bookkeeping, every transaction affects at least two accounts. All transactions are categorized according to account. The accounts you use for categorizing transactions are listed in your chart of accounts.
For instance, if you sell produce to a buyer, you might debit your Cash account and credit your Sales Revenue account.
Or, if you purchase supplies, you would debit your Supplies Expense account and credit your Cash account.
It can get more complex than that. For instance, if you buy a $30,000 tractor, making a $10,000 down payment and paying the rest with a loan, you might debit Equipment $30,000, credit Cash $10,000, and credit Notes Payable $20,000.
For more detailed versions of these examples, and a deeper dive into double-entry bookkeeping, check out our introduction to journal entries or our practical guide to debits and credits.
The bottom line is that, by preparing a trial balance, you’re making sure all the debits and credits balance out so you can catch common mistakes before they show up in any financial statements.
Double-entry account categories
Each account you use in your double-entry bookkeeping system falls under a particular category. And each of these categories has a “normal balance” that’s either a debit or a credit.
| Account Category | Examples | Normal Balance |
|---|---|---|
| Asset | Cash, Inventory, Equipment | Debit |
| Liability | Accounts Payable, Notes Payable | Credit |
| Equity | Owner’s Capital | Credit |
| Revenue | Crop Sales, Repair Income, Hauling Income, Livestock Sales | Credit |
| Expense | Feed, Supplies, Materials, Subcontractors | Debit |
Your own chart of accounts may look a bit different. The important thing to remember is that, when you prepare a trial balance, all of the credits and debits should balance out.
How to prepare a trial balance
If you have many journal entries to go through, preparing a trial balance by hand can be a lengthy process. That being said, the steps you follow are fairly straightforward:
List all accounts. Each row in your list of accounts includes two columns: one for debits, another for credits. Record the ending balance for each account as either a debit or a credit.
Add up all the amounts in the debit column. Record the total at the bottom of the column.
Add up all the amounts in the credit column. Record the total at the bottom of the column.
Compare the total for each column. If your trial balance is free of errors, the two amounts will be identical.
Check for errors. If the two totals for debits and credits differ, you need to identify the source of the error. More on that below.
Accounting software like Ambrook can automatically build this report for you. Find and export it by following these steps:
Go to Settings, then Export.
Scroll down to Other and click on Trial Balance.
Select the date you want to run a trial balance for, the accounting basis, and the format you want it in.
This saves you the time, trouble, and potential errors of manually calculating a trial balance.
Adjusted vs. unadjusted trial balances
If you use the accrual method of accounting, you may need to prepare two trial balances: an unadjusted trial balance, and an adjusted trial balance.
Quick refresher: The cash basis method of accounting records transactions based on when money changes hands. The accrual method records transactions based on when you earn revenue or incur expenses, regardless of when cash changes hands. (For more, see Understanding Accounting Methods: Cash vs Accrual Basis.)
For example, suppose you sell grain to a buyer in October, but they don’t pay you until November. With the cash method, you record the sale in November, when you collect payment. With the accrual method, you record the transaction in October, when you make the sale, even though you haven’t received payment.
So if you’re following the accrual method, you’ll prepare an adjusted trial balance to make sure you capture revenue and expenses in the period they belong to. For example, that could include revenue you’ve earned but that hasn’t landed in your bank account yet, or expenses you incurred but haven’t yet paid.
You do this by first preparing an unadjusted trial balance, listing your total debits and credits exactly as they appear in your general ledger. Then, you’ll record adjusting journal entries before running an adjusted trial balance with them. Your accountant can often help with this process to make sure everything looks correct.
Finally, with your adjusted trial balance, you can generate an income statement, a balance sheet, and a statement of cash flows.
All of this can be complex, especially when you’re starting out. That’s why accounting tools like Ambrook will prepare these reports from your ledger automatically, taking into account the accounting method you choose. You and your accountant just worry about reviewing the reports for accuracy, instead of having to generate them by hand.
Trial balance example
Talking about trial balances in the abstract, it can be hard to get a picture of what a completed trial balance looks like.
Here is an example trial balance, as of August 31, for a small farm using cash basis accounting. For simplicity, let’s say it only covers financial activity from August.
Trial balance for the month ending August 31
| Account Name | Debit ($) | Credit ($) |
|---|---|---|
| Cash | 18,500 | |
| Crop Sales Revenue | 12,000 | |
| Livestock Sales Revenue | 5,000 | |
| Government Subsidy Income | 2,000 | |
| Owner’s Equity | 12,500 | |
| Feed Purchases | 3,500 | |
| Seed & Fertilizer Purchases | 2,200 | |
| Fuel and Oil Expense | 1,300 | |
| Equipment Repairs | 1,000 | |
| Utilities Expense | 800 | |
| Wages Paid | 3,200 | |
| Insurance Premium Paid | 1,000 | |
| Totals | 31,500 | 31,500 |
Note that the Cash account lists the total cash assets held by the business after taking into account revenue and expenses.
Here are the financial activities reflected in the trial balance:
Owner’s equity of $12,500
Sales of harvested crops totaling $12,000
Sales of livestock totaling $5,000
Government subsidy payments totaling $2,000
Feed purchases totaling $3,500
Seed and fertilizer purchases totaling $2,200
Vehicle costs (Fuel and Oil Expenses) totaling $1,300
Equipment repairs costing a total of $1,000
Utilities payments totaling $800
Wages paid totaling $3,200
Insurance premiums totaling $1,000
A total cash balance, at the end of the month, of $18,500
Common trial balance errors (and how to fix them)
If the total debits and credits in your trial balance don’t match, there is an error. That error could either be one you made while preparing the trial balance, or it could be an error in your general ledger.
Here are some common mistakes to look out for:
Mathematical errors
The first place to look for errors is the trial balance itself.
If you incorrectly added up your total debits or total credits, it could be the reason the totals don’t match. Do the math again to make sure you didn’t leave anything out.
If that doesn’t work, compare each account on the trial balance with its ending balance in your general ledger. Maybe an account was left out, duplicated, or the wrong amount was copied.
Single-sided entries
If you enter a transaction with only debits or only credits in the general ledger, it will result in a single-sided entry. That means you recorded a debit without recording the matching credit(s), or vice versa.
The only way to correct this error is by carefully reviewing your general ledger and making sure that each entry has one or more matching entries that balance it out.
Unequal debit or credit entries
You can make an error in your general ledger by entering a transaction and then entering its balancing transaction incorrectly.
For instance, if you debited Supplies $5,000, but only credited Cash $500, the entries would be unequal. They would also be unequal if you debited Supplies $5,679 and credited Cash $5,697.
Here’s a shortcut for finding errors: on your incorrect trial balance, determine the difference between your total debits and total credits. If the difference is divisible by 9, it could mean that the digits were switched in an entry (e.g., 97 instead of 79).
Wrong side postings
You will run into problems with your trial balance if one of your ledger entries that was meant to be a credit was actually recorded as a debit, or vice versa.
For instance, if you record a cash receipt as a credit to Cash rather than as a debit, the error will be reflected in your trial balance.
Calculate the difference between total debits and total credits on your trial balance. If the difference is divisible by 2, it may mean a wrong side posting is the reason for the mismatch between the two totals.
Errors a trial balance won’t catch
Note that while a balanced trial balance is a good sign, it doesn’t necessarily mean there are no errors in your books at all. For example, these kinds of mistakes might not show up in your trial balance:
Transactions that were never recorded at all
Transactions that were recorded twice
Entries booked to the wrong account, but on the correct side
An incorrect transaction amount that was entered on both sides of an entry
To catch these kinds of errors in your books too, make sure to reconcile your accounts at the end of the month and work with your accountant to check that everything looks accurate.
Frequently asked questions (FAQs) about trial balances
Let’s review some of the most common questions about trial balances.
What is the purpose of a trial balance?
A trial balance checks that total debits equal total credits across your books. It’s a quick way to spot recording errors before you prepare financial statements or hand your books to an accountant.
What’s the difference between a trial balance and a general ledger?
Your general ledger lists every transaction in your books, organized by the account. A trial balance lists your accounts’ ending balances at a given point in time; it isn’t a running record of all your transactions.
What’s the difference between an unadjusted trial balance and an adjusted trial balance?
The unadjusted trial balance reflects your books and account balances before any adjusting entries were made. The adjusted trial balance includes those adjusting entries (e.g., to account for things like revenue you earned but haven’t received in your bank account yet).
Does a trial balance include income and expense accounts?
Yes. Unadjusted and adjusted trial balances include income and expense accounts as well as assets, liabilities, and equity.
Do I need a trial balance if I use accounting software?
Your accounting software can make your books less prone to recording or data entry errors, but it’s still a good idea to review a trial balance regularly. This way, in the event that there is a mistake, you can catch it early. Accounting tools like Ambrook can run a trial balance for you, so you don’t have to do it manually.
Ambrook helps you find the right balance
If you’re losing sleep over bookkeeping errors and manually running trial balances, there’s an easier way to make sure your books are accurate and balanced. Ambrook automatically imports your transactions, helps you reconcile your accounts, and generates a trial balance whenever you need it, so you can spend less time worrying about mistakes. Try it free for 30 days.
This resource is provided for general informational purposes only. It does not constitute professional tax, legal, or accounting advice. The information may not apply to your specific situation. Please consult with a qualified tax professional regarding your individual circumstances before making any tax-related decisions.