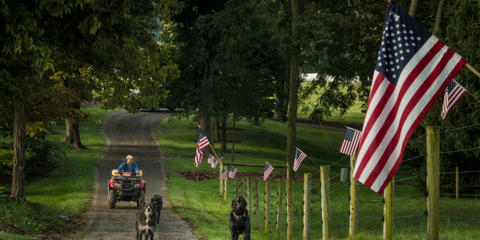
The Department of Veterans Affairs’ (VA) Home Loan benefit may be used to purchase a farm. There must be a farm residence on the land, and the Veteran must live in it as his or her primary residence. VA-guaranteed loans can only be used for residential purposes, and not to purchase a business. This means that some farm properties may not be eligible for purchase using a VA-backed home loan.
Eligibility
You must be a Veteran (or otherwise hold VA home loan entitlement) and you must live in the farm's house. This is the VA home loan benefit applied to a farm property — it is not farm business financing.
Who. Eligibility runs through a VA home loan Certificate of Eligibility (COE). "You may be able to get a COE if you meet the minimum active-duty service requirements for your service period or were discharged under a qualifying exception." For service from August 2, 1990 to the present that is "at least 90 continuous days"; for September 8, 1980–August 1, 1990, "at least 181 days." National Guard members qualify with "At least 90 days of non-training active-duty Title 10 service" or "6 creditable years in the National Guard"; Selected Reserve members with "At least 90 days of non-training active-duty service" or "6 creditable years in the Selected Reserve." Surviving spouses may qualify if "eligible for or currently receiving certain types of VA Dependency and Indemnity Compensation (DIC)," or as "the spouse of an active-duty service member who's missing in action (MIA) or being held as a prisoner of war (POW)." "If you've received an other than honorable, bad conduct, or dishonorable discharge, you may not be eligible for VA benefits."
The property tests — where farm purchases actually fail.
-
"There must be a farm residence on the land, and the Veteran must live in it as his or her primary residence."
-
"VA-guaranteed loans can only be used for residential purposes, and not to purchase a business. This means that some farm properties may not be eligible for purchase using a VA-backed home loan."
-
The appraisal must support residential use: "The appraisal of properties with acreage should not pose a problem, as long as similar properties in the area were recently sold primarily for residential use."
-
"For VA purposes, the value must not include livestock, crops, or farm equipment and supplies." Barns, sheds, corrals, stables and pastures are valued at fair market value, but the loan remains a residential loan.
No acreage limit. "VA does not limit the number of acres a VA-guaranteed property may have."
If farm income is what qualifies you. "Some or all of the income necessary to support the loan payments may come from farming operations. In this case, VA must verify the Veteran's ability and experience as a farm operator" — analyzed under the "Self-Employment Income" procedures in Chapter 4 of VA Pamphlet 26-7, the Lenders Handbook.
Also. "To get financing for a VA-backed home loan, you must meet credit, income, and occupancy requirements from both the VA and your lender." National — no state restriction. First step is the COE: apply online or file VA Form 26-1880; lenders can also pull COEs for Veterans online.
Details
Organization
Financial Instrument
Loan
Terms
Loans for farm dwellings are appraised the same way as for nonfarm-type dwellings:
-
VA does not limit the number of acres a VA-guaranteed property may have.
-
The appraisal of properties with acreage should not pose a problem, as long as similar properties in the area were recently sold primarily for residential use. This may include improvements not typically considered residential, like barns, sheds, corrals, stables and pastures.
-
For VA purposes, the value must not include livestock, crops, or farm equipment and supplies. Individual improvements not typically considered residential will be valued at fair market value. This includes barns, sheds, corrals, stables, pastures, etc.
Underwriting guidelines are generally the same as for nonfarm-type dwellings.
-
For example, some or all of the income necessary to support the loan payments may come from farming operations. In this case, VA must verify the Veteran's ability and experience as a farm operator. Updated August 2018 2
-
The procedures and analysis in Chapter 4 of VA Pamphlet 26-7, "Lenders Handbook", under "Self-Employment Income" generally apply.
Application Instructions
-
Apply for a Certificate of Eligibility (COE). You can apply online using eBenefits at www.ebenefits.va.gov/, or fill out VA Form 26-1880, "Request for Certificate of Eligibility." Download the form from www.vba.va.gov/pubs/forms/vba-26-1880-are.pdf. See page 2 of the form for the mailing address of your regional loan center. Lenders can also get COEs for Veterans online.
-
Find a realtor and lender to help you through the process of buying a home. The lender will complete an application and help you determine the amount you qualify for. Once prequalified or pre-approved, the realtor can show you homes within your price range.
-
Choose a home, and sign a purchase agreement with the seller or a contract with a builder. Your sale contract should include a provision that voids the sale if you are unable to get VA-guaranteed financing.
-
The lender will order an appraisal of the property. Lenders also help you clear the final conditions required to close on your new home.
Related Programs
Direct Farm Operating Loan
Farm Service Agency
- LoanGeneralEquipmentAnimal PurchaseDiversificationMarketingProcessingFeedSeedFertilizerCash RentHousingConstructionInfrastructureRepairsPest ManagementStorageLegal & FinanceWater ManagementWaterway ProtectionWater QualityConservationTrainingImmigrantsCSARefinancingReduced TillageNationalAny
Environmental Quality Incentives Program (EQIP)
Natural Resources Conservation Service
- GrantCost ShareConservationCover CropsForest ManagementCertified GrassfedIrrigationHigh TunnelCertified OrganicAir QualityAlternative EnergySoil HealthWildlife & Pollinator HabitatWater QualityWeatherResearchLandscapePrecision AgDroughtNutrient ManagementCarbon CaptureFencingAgroforestryGrazing ManagementReduced InputsNationalAny
Farm Storage Facility Loan Program (FSFL)
Farm Service Agency
- LoanInfrastructureEquipmentStorageLightingDelivery VehicleNationalOilseedsPeanutsPulse CropsHayHoneyBiomassFruitsVegetablesFloricultureHopsMaple SapMilkCheeseYogurtButterEggsRyeAquaculturePoultryLivestockGrains
ACRE3 Agricultural Energy Efficiency
Colorado Department of Agriculture
- GrantCost ShareLoanAlternative EnergyConservationIrrigationStorageGreenhouseCOAny
Updated September 4, 2026
Image Credit: U.S. Department of Agriculture
This information was gathered from public sources. Ambrook is not responsible for or able to affect the results of any financial programs listed, nor are they responsible for any incorrect information that is listed or is on the hyperlinked external sites. All information is subject to change.
Explore hundreds more programs on Ambrook.